Skip to content

Build to Rent: 61,700 Units, Risks Investors Must Model

Build-to-rent is a viable, income-oriented real estate strategy for investors who can underwrite phased lease-ups and operationally manage dispersed single-family communities. The sector has shifted from rapid, growth-chasing expansion toward a more selective, income-focused posture, and the biggest risks now sit in construction costs, lease-up pacing, and exit cap rates rather than in demand itself. What follows breaks down the current data, the underwriting mechanics, a practical deal-evaluation checklist, and how professional management changes the math.


TL;DR:

  • As of early May 2026, about 61,700 units were under construction, over 60% in the South; local job growth, migration, and permitting deserve close review.
  • Model operating expenses at 35% to 45% of effective gross income, and size deficit reserves to the deal’s absorption case, not a generic percentage.
  • Stress test a 50 basis point exit cap rate increase, and forecast lease up by monthly unit deliveries tied to occupancy approvals.
  • Before committing, verify entitlement status, HOA covenants, warranties, forward purchase protections, and completion guarantees; favor the sponsor’s actual lease up record over projections.
  • Investors without operating capacity should secure an experienced partner and hold through stabilization; quick flips carry construction and lease up risk.

Aubenrealty
Make Build-to-Rent Easier to Manage
Auben Realty provides property management, renovation, and tenant placement services for investors seeking comprehensive support.

Explore Auben Realty

Table of Contents

What Is Build-to-Rent and How Does It Differ From Other Rental Models?

Build-to-rent (BTR) refers to purpose-built rental communities, typically detached single-family homes, paired townhomes, or small cottage-style units, designed and constructed from the ground up as rental housing rather than for-sale product. Unlike scattered-site single-family rentals, which are individually acquired homes spread across a city, BTR communities are planned as cohesive developments with shared amenities, centralized leasing offices, and unified branding.

The format sits between two established asset classes. It offers the privacy and space of a single-family home with the operational centralization of a multifamily apartment complex. That distinction matters for underwriting, because BTR communities carry some multifamily-style efficiencies (one leasing team, one maintenance crew) while also inheriting single-family-style costs (more roof area, more landscaping, more linear feet of infrastructure per unit).

Key operational features that separate BTR from both comparables include:

  • Community-level amenities, such as pools, dog parks, or clubhouses, shared across the rental population rather than attached to a single home.
  • HOA governance structures, often established by the developer and later transferred to the operator or investor group.
  • Centralized property management, with one operator handling leasing, maintenance, and resident retention across the entire community instead of a patchwork of individual landlords.

Readers who want a deeper look at how community design shapes long-term performance can review this build-to-rent strategy overview.

Where Is the Build-to-Rent Pipeline Concentrated Right Now?

The development pipeline has cooled from its 2024 peak but remains substantial. As of early May 2026, roughly 61,700 BTR units were under construction nationwide, with the South accounting for more than 60% of that total, about 37,400 units, while the West held roughly 13,000 units under construction.
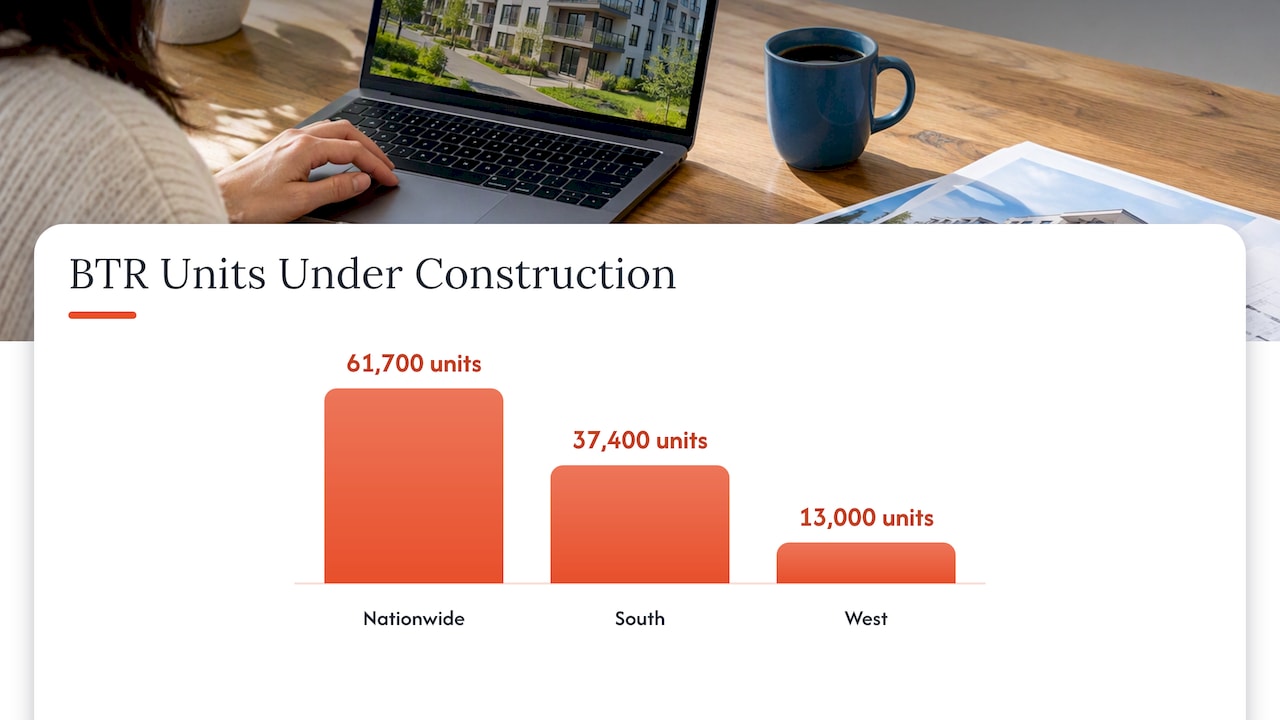
BTR construction units by region

Supply peaked in early 2024 and has since declined by roughly 50% through the first quarter of 2026, according to quarterly data tracked by the National Apartment Association, signaling a market that is recalibrating rather than retreating. Demand has stayed resilient even as developers pull back on new starts, which is the clearest evidence that BTR is maturing into an income-oriented asset class rather than a pure growth play.

A few patterns matter most for underwriting decisions:

  • Sun Belt concentration means regional job growth, migration trends, and local permitting speed carry outsized weight in deal selection.
  • Deliveries are expected to moderate further into 2027 through 2029, based on RealPage’s later-quarter regional forecasts, which should ease near-term competitive pressure on lease-up.
  • National rent growth remains muted, with Freddie Mac’s multifamily outlook flagging growth near 2.2% alongside a vacancy uptick toward 6.2% in the broader rental market, a backdrop that rewards operators who can hold occupancy rather than chase rent spikes.

Why Are Investors Allocating to Build-to-Rent Now?

The core appeal of BTR is a cash-flow profile that behaves more like stabilized multifamily income than speculative single-family appreciation. Renter households in BTR communities tend to stay longer than in scattered-site rentals, partly because the product offers home-like space without the financial commitment of ownership, which reduces turnover costs and vacancy drag.

Scale is the other half of the thesis. A single operator managing 150 units across one or two communities can centralize maintenance dispatch, standardize vendor contracts, and deploy a single technology stack for leasing and rent collection, all of which protect net operating income in ways that scattered single-family portfolios struggle to replicate.

Rental premiums in BTR typically come from a few sources:

  • Space and privacy that a comparable apartment unit cannot offer, including private yards and attached garages in many communities.
  • Amenity access bundled into rent rather than charged separately, which supports retention.
  • Location flexibility, since BTR developers can build in suburban and exurban submarkets where land costs are lower but renter demand (often driven by affordability pressure relative to homeownership) remains strong.

Pro Tip: Underwrite turnover assumptions conservatively even with favorable retention data; a single bad lease-up quarter can erase a year of projected savings from lower churn.

What Underwriting Risks and Mechanics Should You Model?

BTR underwriting carries risks that differ meaningfully from stabilized multifamily acquisitions, because much of the capital is deployed before the asset produces any income.

  1. Entitlement risk: zoning approvals, HOA formation, and permitting timelines can slip, delaying the start of construction and the clock on interest carry.
  2. Construction-cost overruns: material and labor cost inflation can erode development spread even when the underlying rent thesis holds.
  3. Slow lease-up: unit-by-unit absorption that lags the pro forma directly extends the period the asset burns cash before covering debt service.
  4. Operating expense inflation: landscaping, road maintenance, and dispersed-footprint costs tend to push BTR expense ratios higher than comparable multifamily assets.
  5. Exit cap-rate risk: a widening of cap rates at sale, even without any operational shortfall, can compress or eliminate projected equity returns.

On the numbers side, practitioner underwriting guidance points to BTR operating expense ratios commonly landing in the 35% to 45% range of effective gross income, higher than typical garden-style multifamily, reflecting the cost of maintaining a low-density, geographically spread community. The same guidance recommends sizing leasing and operating deficit reserves to the sponsor’s specific absorption case rather than applying a generic reserve percentage, since lease-up velocity assumptions drive interest carry and stabilization timing more than almost any other input.

Forward-purchase and phased acquisition structures, where an investor commits capital before construction completes and closes on units as they deliver, have become common in BTR deals. These structures shift some development risk away from the eventual owner but can also leave investors with limited control over HOA formation and construction decisions until the final closing, so contractual protections around document access and warranty schedules matter as much as the pricing itself.

How Do You Evaluate a Build-to-Rent Deal Before Committing Capital?

A disciplined diligence process turns a sponsor’s pro forma into a defensible investment decision. Start with the core metrics, then stress-test them, then interrogate the paperwork.

  1. Calculate the development spread between projected stabilized value and total cost, including land, hard costs, soft costs, and carry.
  2. Project stabilized net operating income using a realistic expense ratio rather than the sponsor’s base case alone.
  3. Run IRR sensitivity against cap-rate movement, since even a 50-basis-point widening at exit can materially change equity returns.
  4. Check debt service coverage at stabilization, not just at the sponsor’s optimistic leasing pace.
  5. Model lease-up on a unit-per-month basis, tied to certificate-of-occupancy milestones, rather than accepting a building-level absorption assumption.

This kind of grid, as outlined in BTR development-risk analysis, quickly reveals which deals have real cushion and which are underwritten to perfection.

Your due-diligence packet should also cover entitlement status, the draft HOA covenants, builder warranty terms, the specific protections in any forward-purchase contract, and any completion guarantees the sponsor is offering. For the capital stack side, lenders increasingly expect detailed rent-roll underwriting support before committing construction or bridge financing, so having that documentation ready speeds up the process.

Pro Tip: Ask every sponsor for their actual trailing lease-up pace on a comparable community, not just their projected pace on the deal you’re underwriting.

How Does Professional Management Change Build-to-Rent Outcomes?

Operational execution is where BTR returns are won or lost after the lease-up phase ends. Drawing on extensive experience managing many properties across multiple regional markets, our team has seen firsthand how centralized operations control cost growth in low-density, dispersed communities.

A few levers make the biggest difference:

  • Pod-based team structures that keep a dedicated group accountable for leasing, maintenance, and resident relations within a single community.
  • In-house maintenance capacity, which shortens response times and reduces the margin vendors typically add to repair costs.
  • Proactive resident retention programs that reduce turnover before it shows up as vacancy loss.
  • Transparent vendor selection and technology-enabled workflows that keep reporting accurate for investors tracking reserves and absorption against the original underwriting.

Investors who partner with an operator experienced in this asset class can set tighter reserve assumptions and more realistic absorption timelines from day one. For more detail on how density and layout affect ongoing maintenance costs, see our analysis of build-for-rent density tradeoffs.

Who Should Actually Pursue a Build-to-Rent Strategy?

BTR rewards investors who either have operational capability in-house or a committed partner who does. Passive capital chasing a quick flip should look elsewhere: the development-forward, shorter-hold version of this strategy only works for sponsors comfortable managing construction risk and lease-up uncertainty directly.

Investors seeking long-term income, by contrast, are better served holding through stabilization and into a multi-year operating phase, where retention and expense discipline compound. The practical takeaway: match your capital’s patience to the deal’s actual timeline, not the other way around.

— MediaBeast

How Auben Realty Supports Build-to-Rent Investors

We bring the operational side of build-to-rent together with the transaction side, so you’re not stitching together separate vendors for acquisition, construction oversight, and day-to-day management. Our Property Management and Project Management services cover lease-up through stabilization, our Asset Management service handles institutional-style reporting against your underwriting assumptions, and our Brokerage Services team supports acquisition and disposition.
Aubenrealty

If you’re evaluating a build-to-rent opportunity or an existing portfolio, our Multifamily & Build-to-Rent Services page is the place to start a conversation about what a portfolio review would look like for your deal. You can also review a closer look at how our management approach has performed across 2,700 properties.

This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.

FAQ

Is a rental property a profitable investment?

Profitability depends on the market, the purchase basis, and operating expenses relative to rent, but well-underwritten rental properties, including build-to-rent assets, can produce stable cash flow when occupancy and expense ratios stay within the ranges practitioner underwriting guidance outlines. Returns vary significantly by deal, so a property-specific pro forma matters more than a general market assumption.

What does “BTR construction” mean?

BTR construction refers to homes or communities built specifically to be rented rather than sold, often as detached single-family homes, townhomes, or cottage-style units grouped into a single managed community. These projects are designed from the start with centralized leasing, shared amenities, and rental-specific layouts in mind.

Is rent-to-own a good way to build credit?

Rent-to-own arrangements are a separate structure from build-to-rent investing and are not a core feature of most BTR communities; whether one builds credit depends entirely on the specific contract terms and whether payments are reported to credit bureaus. Anyone considering a rent-to-own agreement should review the contract with a qualified professional before relying on it for credit-building purposes.

What does Dave Ramsey say about renting?

Dave Ramsey’s general guidance favors renting over buying when a household is not financially ready for homeownership, framing renting as a reasonable short-term choice rather than a failure. For investors, that same affordability gap between renting and owning is part of what sustains renter demand across the single-family and build-to-rent markets, as explored in our breakdown of homeownership versus renting costs.

Sources

Leasing Only Services: 5 Steps, FCRA Rules, and a Landlord Checklist

A leasing only service handles tenant placement, meaning it markets your property, screens applicants, and signs the lease, while you keep running day-to-day operations yourself. It fits owners who want a professional hand finding and vetting tenants without handing over ongoing management. The typical cost is a one-time fee, often a flat rate or approximately equal to a month’s rent, paid when a tenant signs.


TL;DR:

  • Standard packages usually include listing creation, rental platform distribution, showings, applicant screening, and lease preparation; photography upgrades and move in reports may cost extra.
  • Placement fees usually cover marketing, showings, screening, and lease preparation; rent collection, maintenance, and renewals remain your responsibility unless separately contracted.
  • Before signing, verify the screening provider, report contents, record lookback policy, advertising platforms, sample lease, and how denied applicants receive notices.
  • Landlords remain responsible for outsourced screening under fair housing and consumer reporting rules; negative report items older than seven years generally cannot appear.
  • The IRS generally treats leasing commissions as deductible rental expenses, but some commissions related to mortgages must be capitalized; confirm the distinction with a tax professional.

Aubenrealty
aubenrealty.com
Place Your Next Tenant With Less Work
Auben Realty provides tenant placement services as part of its property management offering, helping owners find renters without managing every detail themselves.

Explore Auben Realty

Table of Contents

Overview of typical lease-only scope and optional add-ons

A standard lease-only package covers the work needed to get a qualified tenant into your unit and stops there. Most providers include:

  • Listing creation with photos and a written description built for rental search sites.
  • Syndication across major rental platforms to reach active renters quickly.
  • Scheduled showings or self-tour access coordinated on your behalf.
  • Application intake and a documented screening process.

Beyond that baseline, many providers offer add-ons such as professional photography upgrades, expanded syndication to niche or local sites, custom lease addenda for pets or parking, and a move-in inspection report with photos. Deliverables and timelines are usually spelled out in a service agreement before you sign, so you know what’s included and what costs extra before the listing goes live. Reviewing that agreement closely helps you avoid surprises once the process starts, since lease-only providers vary widely in how much marketing reach and screening depth they build into the base fee.

Step-by-step duties performed during the leasing process

Here’s what actually happens between hiring a lease-only provider and handing you the keys to a signed lease:

  1. Pricing the unit. A rent analysis compares your property against similar local listings to set a competitive asking price.
  2. Building the listing. Photos, floor plans, and copy go live, then get pushed across rental syndication channels, a process detailed in rental listing syndication strategies.
  3. Running showings. Agents schedule in-person tours or set up self-tour technology for prospective renters.
  4. Screening applicants. Credit, eviction, and background checks get pulled, reviewed against written criteria, and documented.
  5. Executing the lease. The provider prepares lease paperwork, collects the security deposit and first month’s rent, and passes tenant details to you for ongoing management.

Pro Tip: Ask upfront exactly where the provider’s responsibility ends, specifically whether they coordinate key handoff and utility transfer or leave that step to you.

Everything after the signed lease, rent collection, maintenance calls, renewals, stays on your plate unless you’ve separately arranged for ongoing management.

Why landlords pick lease-only instead of handling placement themselves

Self-managing landlords often underestimate how much professional marketing and screening speed up placement. A lease-only provider typically brings:

  • Wider marketing reach through syndication networks most individual owners can’t access alone.
  • Fewer vacancy days thanks to faster, more consistent showings and follow-up.
  • Lower recurring costs than a full-service monthly management contract, since you only pay once per placement, a gap explored in this leasing fee versus management fee comparison.
  • Full control over vendor selection, rent collection, and maintenance decisions after the tenant moves in.

Leasing commissions and tenant-placement fees are generally deductible as rental expenses on Schedule E, according to IRS Publication 527, which often offsets much of the upfront cost. A tax professional can confirm how that applies to your specific filing situation.

Tenant screening, FCRA rules, and HUD guidance on advertising

Outsourcing placement doesn’t transfer your legal responsibility. When a provider pulls a credit or background report on your behalf, that report counts as a consumer report under the Fair Credit Reporting Act, and you’re required to have a permissible purpose and follow proper adverse-action procedures, as outlined by the FTC’s guidance for landlords. Negative items older than seven years generally cannot appear on these reports under FCRA Section 605(a)(5).

HUD guidance on AI and tenant screening warns that automated screening tools and targeted ad delivery can produce discriminatory effects, and housing providers remain responsible under the Fair Housing Act even when screening or advertising is outsourced.

Housing providers retain responsibility for screening outcomes even when using automated tools, regardless of whether a third-party vendor built the model.

Before handing off screening, require:

  • Written screening criteria applied consistently to every applicant.
  • A defined lookback window for criminal and eviction records.
  • A documented adverse-action notice process with applicant dispute rights.
  • Record retention showing how each decision was made.

CFPB reporting on tenant background checks found screening companies frequently produce errors, which makes vendor transparency a practical safeguard against disputes and complaints.

How leasing-only providers charge and typical time-to-lease

Pricing structures vary, but three models dominate the market:

  • A flat fee set regardless of rent amount.
  • A percentage of the first month’s rent, commonly used as the placement fee.
  • A tiered package where higher fees unlock expanded marketing or faster turnaround.

These fees typically cover marketing, showings, screening, and lease preparation, but exclude ongoing services like rent collection, maintenance coordination, or lease renewals. Those require a separate management agreement. Timeline from listing to signed lease depends on local rental demand, pricing accuracy, and how aggressively the unit gets marketed, with well-priced, well-marketed units typically moving faster than units sitting stale on fewer platforms.

On the tax side, IRS guidance treats leasing commissions as deductible rental expenses, while certain mortgage-related commissions must be capitalized instead of deducted outright. That distinction is worth raising with your accountant before year-end filing.

Single checklist to evaluate and hire a lease-only provider

Use this sequence when comparing providers:

  1. Check screening transparency. Ask which screening partner they use, what’s included in the report, and their lookback window policy, a process explained in how property management companies handle tenant screening.
  2. Review advertising reach. Confirm which platforms they syndicate to and whether photography is included or an add-on.
  3. Request a sample lease. Read the actual lease language you’d be signing tenants to, not just a summary.
  4. Ask about adverse-action handling. Get specifics on how denied applicants are notified and what documentation they receive.
  5. Request references. NARPM’s hiring guidance recommends verifying a provider’s screening, reporting, and lease-enforcement track record before signing.

Pro Tip: Treat vagueness about screening sources or an unlimited criminal lookback window as a red flag, not a minor detail.

How Auben Realty applies these practices for tenant placement

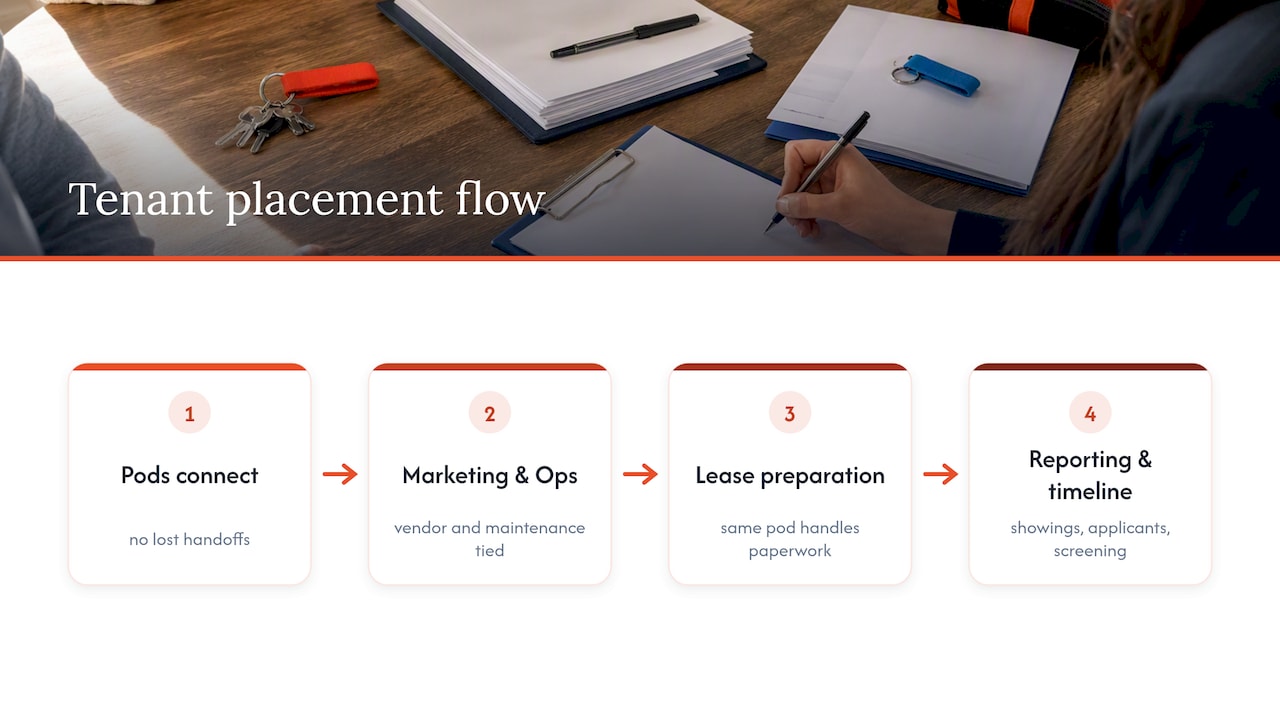
Our team built a pod-based structure so tenant placement doesn’t get lost in handoffs between departments. Maintenance and vendor coordination mean the person marketing your listing stays connected to the person preparing your lease paperwork. When tenant placement is handled, owners receive clear reporting on showing activity, applicant status, and screening outcomes, plus a documented timeline from listing to signed lease so there’s no guessing about where things stand, with helpful guidance on how to sell a house with tenants if needed later.

How Auben Realty applies these practices for tenant placement — overview diagram

Who lease-only actually fits

Lease-only works best for owners who are comfortable handling maintenance calls and rent collection themselves but want professional marketing and screening to fill vacancies faster. If that’s you, getting a quote and preparing a basic property checklist, photos, rent comps, move-in condition, is the fastest way to start. Our team offers that as a direct next step.

— MediaBeast

Start tenant placement without the DIY workload

Finding and vetting tenants takes real time, and a bad screening process can cost you more in vacancy days and turnover than the fee ever would. We handle the marketing, showings, and screening so you spend less time chasing leads and more time running your property the way you want.

Aubenrealty

What this looks like in practice:

  • A rent analysis and listing built to perform on major rental sites.
  • Screening backed by documented criteria and a clear adverse-action process.
  • Direct reporting so you always know where your placement stands.

If you’re ready to see what tenant placement through our property management services looks like for your property, reach out and get a quote today.

FAQ

What is the 90% rule in leasing?

For rental housing, landlords are more likely to encounter occupancy or renewal benchmarks set by their own portfolio rather than a formal 90% test.

What are the four types of leases?

Common lease classifications include gross leases, net leases, modified gross leases, and percentage leases, each differing in how expenses like taxes, insurance, and maintenance are split between landlord and tenant. Residential leasing-only services typically work with standard gross leases rather than the commercial variants.

What is the 1.5 rule when leasing a car?

It doesn’t apply to residential property leasing, which uses rent comparables and local market analysis instead.

What are the three main types of leases?

Residential leasing typically involves fixed-term leases, month-to-month agreements, and sublease arrangements, each offering different levels of flexibility for landlords and tenants. A lease-only provider can prepare any of these formats depending on what fits your property strategy, as covered in this overview of month-to-month lease benefits.

How long does a leasing-only service typically take to fill a vacancy?

Turnaround time depends on local rental demand, how competitively the unit is priced, and how broadly it’s marketed, with well-priced listings generally moving faster than units with limited syndication. Ask any provider for their average days-on-market figure before signing an agreement.

Sources

Primary sources for landlord compliance and tax guidance

These sources informed the legal and financial points covered above:

Get a Dallas Eviction Hearing in 10–21 Days: Legal Steps for Landlords

An eviction in Dallas is a forcible-detainer lawsuit that a landlord files in Justice Court after giving the required written notice. If you are a tenant who was served, file an Answer with the court that issued the citation and show up to your hearing. If you are a landlord, confirm your notice was correct and file in the justice precinct where the property sits before anything else.


TL;DR:

  • The default notice period is three days unless the lease changes it; mail adds two days, and hearings occur 10 to 21 days after filing.
  • A summary disposition motion cuts the tenant’s response deadline to four days; tenants facing a squatter allegation must attach documentary proof of tenancy.
  • Tenants should file an Answer before the hearing and bring leases, payment records, repair requests, and landlord communications to support defenses that match their facts.
  • An appeal is due within five days, with a bond, cash deposit, or Statement of Inability to Pay; staying requires rent in the court registry.
  • Dallas County lists an example $134 filing fee, with citation, service, and writ charges separate; confirm current totals with the JP clerk before filing.

Aubenrealty
Reduce the Work of Property Ownership
Auben Realty provides property management, renovation, and tenant placement services for owners seeking less hands-on involvement.

Explore property management

Table of Contents

How long does the Dallas eviction timeline take from notice to writ?

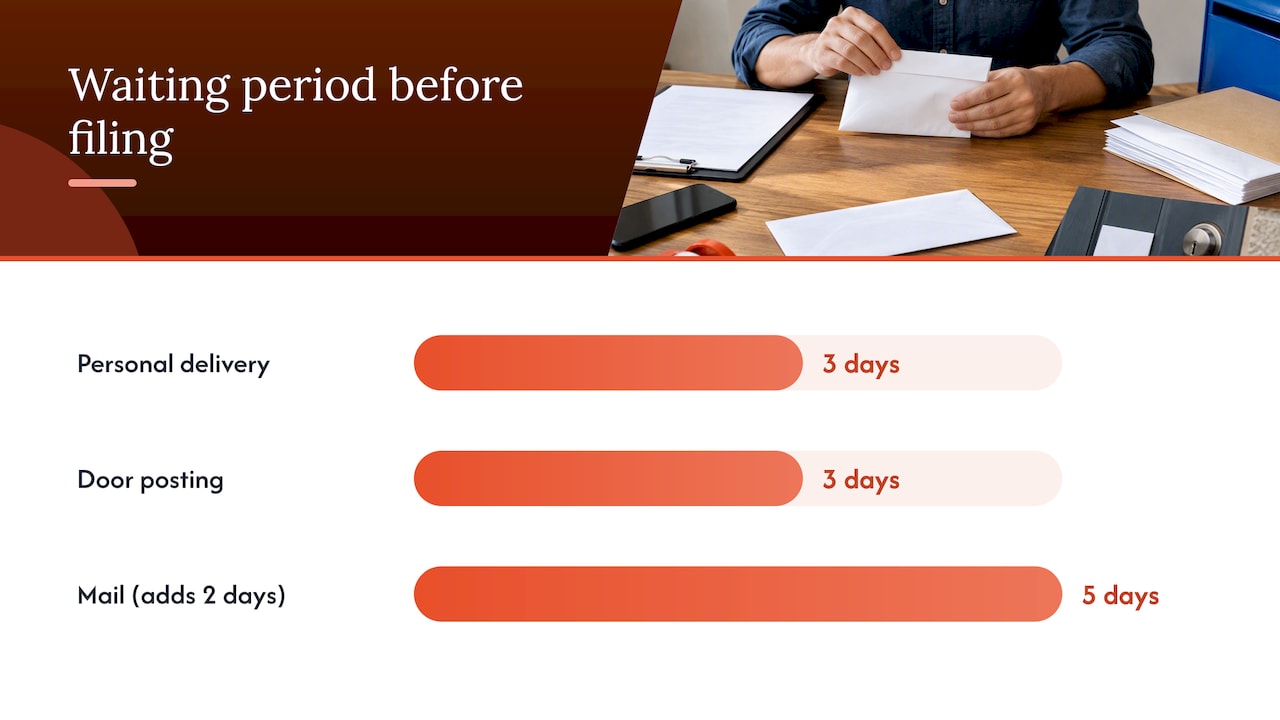
The clock starts the day notice is delivered, and the delivery method changes that date. Hand delivery counts immediately, but mail delivery adds two extra days before a landlord can file. Posting notice on the door also triggers the standard waiting period under Dallas County JP guidance. Once the waiting period passes and the landlord files, most hearings happen 10 to 21 days later, though a Motion for Summary Disposition shortens the tenant’s response window dramatically.

  1. Notice period: three days by default, unless the lease sets a different number.
  2. Filing: the landlord submits a sworn petition to the correct Justice Court.
  3. Hearing: typically scheduled 10 to 21 days after filing.
  4. Summary disposition exception: if filed, the tenant has only four days to respond with proof of tenancy.
  5. Appeal window: the losing side has five days to appeal to county court.
  6. Writ of possession: once issued, constables give 24 hours’ notice before physically removing belongings.

Holidays and court closures can push any of these dates further out, so neither side should treat a calendar estimate as a guarantee.

Which notice applies, and how must it be served in Dallas County?

Which notice applies, and how must it be served in Dallas County? — overview diagram

Nonpayment of rent calls for a Notice to Pay or Vacate, while lease violations or holdover situations call for a plain Notice to Vacate. Both default to a three-day period under Texas eviction law, but a signed lease can extend or shorten that window, so the lease governs first.

Dallas County JP courts recognize three delivery methods, and each affects the filing date differently:

  • Personal delivery: handing the notice to the tenant or someone in the household who is 16 or older.
  • Mail: adds two extra days to the waiting period before the landlord can file, per Dallas County JP procedures.
  • Door posting: taping the notice to the inside of the main entry when no one answers.

Pro Tip: Keep a dated photo of the posted notice and a copy of any mailing receipt, since a challenge to service is one of the most common ways a tenant gets a judgment set aside.

How do you file an eviction in the correct Dallas Justice of the Peace court?

Venue is not optional. Under Texas Property Code Sections 24.004 and 24.0041, the suit must be filed in the justice precinct where the rental property is located, not where the landlord’s office sits or where the tenant now lives.

  • File a sworn petition that follows the Texas Rules of Civil Procedure and the local JP form.
  • Bring an original petition plus a copy for each defendant and one for the filing-stamped record, since Dallas clerks prefer parties arrive prepared rather than requesting copies on site.
  • Confirm you are filing in the correct precinct court before paying, since Dallas County JP court pages list precinct boundaries by address.
  • Ask the clerk about current filing, citation, and service charges, since these are updated periodically.

What should tenants do after receiving an eviction notice?

Receiving a citation is not a judgment. Tenants keep real options if they act quickly and file an Answer in the Justice Court that issued the citation.

  1. File an Answer any time before the hearing, according to the TexasLawHelp defense guide, unless the landlord has filed a Motion for Summary Disposition, which shortens that deadline to four days.
  2. Raise defenses that fit your facts: improper service, payment already made, unaddressed repair requests, retaliation, or mistaken identity if you are not actually the named tenant.
  3. Bring organized proof: the lease, a payment ledger, photos, repair requests, and any written communication with the landlord, each in multiple copies.
  4. If you missed the hearing, ask the court about a Motion to Set Aside the default judgment, since strict deadlines apply.

Pro Tip: A tenant responding to a summary disposition motion on a squatter allegation must attach documentary proof of tenancy within four days, or the court can rule without a trial.

What happens at the hearing, and how does an appeal work?

The hearing itself is informal by Justice Court standards, but it still follows evidence rules, and either side may request a jury in most cases. A summary disposition motion skips the live hearing entirely when the tenant fails to respond in time.

  • If the landlord wins, the losing party has five days to appeal by filing a bond, a cash deposit, or a Statement of Inability to Pay.
  • Staying in the home during an appeal generally requires paying rent into the court registry, with the amount set by the court.
  • Once a judgment becomes final and unappealed, the court issues a writ of possession.
  • Constables must give 24 hours’ notice before carrying out a physical removal under that writ.

What does an eviction cost in Dallas, and what timing quirks matter?

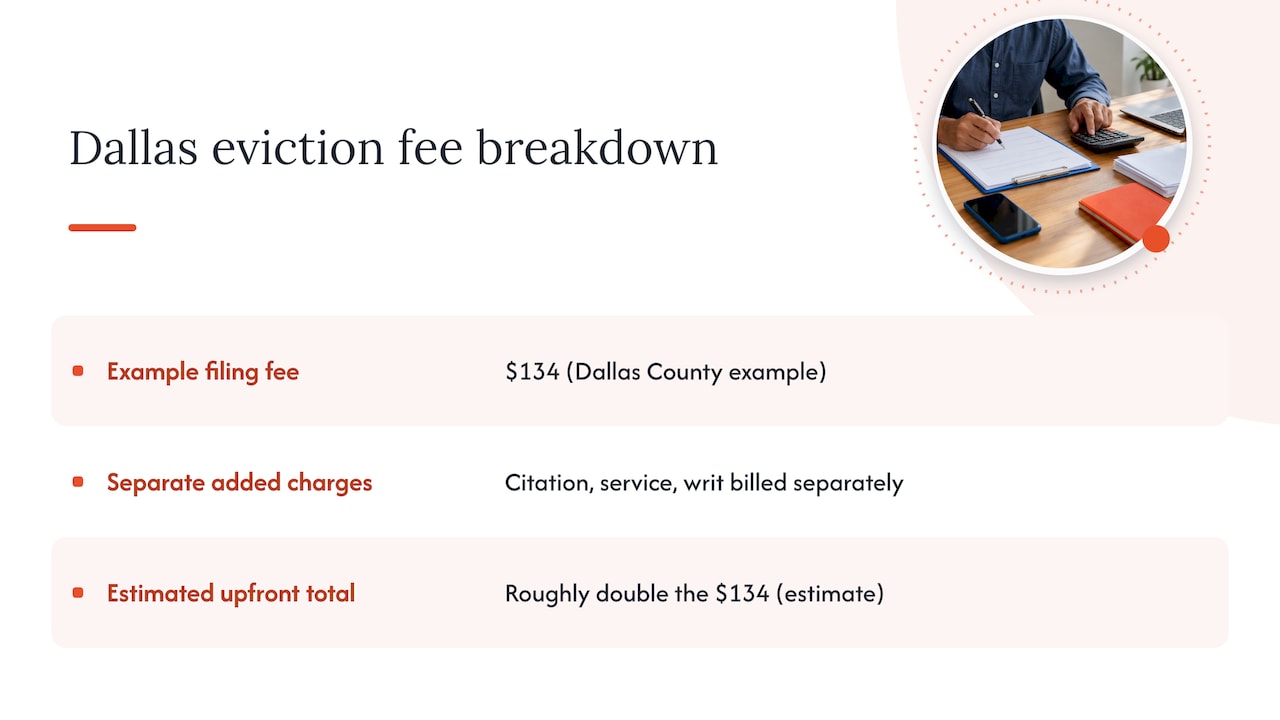
Dallas County lists an example eviction filing fee of $134, with citation, service, and writ charges billed separately, according to the Dallas County filing fees page. Those added charges can roughly double the upfront cost of a straightforward nonpayment case, so budgeting for the lawsuit alone understates what a landlord will actually pay.

Dallas eviction filing fee and additional charges

Timing quirks matter just as much as the dollar figures. Mailing a notice adds two days before the waiting period even starts to run, and a holiday or court closure can push a hearing date by a week or more without warning. Always confirm current fee amounts directly with the Dallas County JP clerk before filing, since schedules are updated periodically.

What should you bring on filing day and hearing day?

Court days move fast, and being unprepared costs time on both sides.

  1. Landlords should bring the lease, a complete payment ledger, the served notice with proof of delivery, photos of any posted notice, and witness names if the case involves a dispute.
  2. Tenants should bring the same lease and ledger, plus repair requests, texts or emails with the landlord, and documentary proof of tenancy if a summary disposition motion alleges otherwise.
  3. At the clerk window, state your case number and precinct clearly, and ask directly whether any paperwork is missing before leaving.
  4. After judgment, act immediately: file an appeal within five days, request a set-aside if you missed the hearing, or begin complying with the writ timeline.

What Auben Realty’s eviction experience teaches Dallas landlords

Most eviction cases fall apart on paperwork, not on the merits. Common issues include challenges to service, incorrect notice forms, or lack of dated payment records, causing cases to restart.

Consistent habits prevent most of that. Using the same notice template every time, logging payments the same way across every unit, and documenting repair requests in writing the moment they come in all reduce the chance a judge finds a procedural gap to exploit. The gap between a clean filing and a dismissed one often traces back to documentation created after the fact instead of in real time.

Not every case needs a lawyer, but those facing contested hearings, retaliation claims, or inconsistent lease histories should consider bringing in counsel or management before the filing date.

— MediaBeast

How Auben Realty helps Dallas landlords manage the eviction process

Aubenrealty

Filing an eviction correctly the first time saves weeks compared to refiling after a dismissed case, and proper handling of notice, documentation, and coordination with legal counsel helps landlords manage Justice Court procedures under deadline pressure.

  • Property management includes tracking lease terms, payment history, and notice timing to help filings hold up under challenge.
  • In-house maintenance aims to resolve repair complaints quickly, which can prevent tenant defenses.
  • Tenant communication involves keeping documented records of notices and exchanges, supporting contested hearings.

If you are weighing whether to self-manage a difficult eviction or hand it to a team that has coordinated hundreds of these cases, start with our Dallas property management page to see how we work, or reach out through our property management services to talk through your specific case.

This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.

FAQ

How long does a Dallas eviction usually take from notice to hearing?

Most Dallas hearings are scheduled 10 to 21 days after the petition is filed, following a notice period that defaults to three days unless the lease says otherwise. Mailing the notice adds two extra days before that clock even starts.

Can a landlord evict a tenant without going to court in Dallas?

No. Every eviction in Dallas requires a forcible-detainer suit filed in the Justice Court for the precinct where the property is located, and a judge must rule before a tenant can be removed.

What happens if a tenant does not respond to an eviction notice in Dallas?

If a tenant never files an Answer and misses the hearing, the court can enter a default judgment, and a writ of possession can follow once the five-day appeal window passes. A missed hearing can sometimes still be addressed through a Motion to Set Aside, but strict deadlines apply.

How much does it cost to file an eviction in Dallas County?

Dallas County lists an example eviction filing fee of $134, with citation, service, and writ fees charged separately. Exact current amounts should be confirmed directly with the JP clerk before filing.

Can a tenant stay in the home while appealing a Dallas eviction judgment?

Yes, but generally only by paying rent into the court registry in an amount the court sets, and by filing the appeal within five days of judgment. Filing a bond, a cash deposit, or a Statement of Inability to Pay is required to perfect the appeal.

Sources

For Investors: Single Family or Multifamily? A 7 Step Decision Checklist

If you need cash flow and scale, multifamily usually wins; if you need liquidity and appreciation optionality, single-family often wins. Multifamily brings denser income and faster portfolio growth but comes with commercial financing rules once you cross five units. Single-family stays simpler to finance and sell but puts your income at the mercy of one tenant per property. Read on for the financing math, management trade-offs, and a checklist to apply to your next deal.


TL;DR:

  • Multifamily properties offer higher cash flow stability and portfolio scaling benefits but require commercial financing for five or more units.
  • Single-family homes are simpler to finance, sell, and often appreciate faster, making them ideal for investors prioritizing liquidity and appreciation.
  • The new 2025 HUD financing rules favor smaller deals, but five-plus-unit properties face stricter commercial underwriting with potential refinancing risks.
  • Managing multifamily units benefits from economies of scale and on-site staffing, while single-family portfolios spread risks across different neighborhoods.
  • Investors should evaluate their primary goals and run detailed financial analyses before choosing between single-family and multifamily investments.

Aubenrealty
aubenrealty.com
Build A More Manageable Portfolio
Auben Realty helps investors manage properties, renovations, and tenant placement while reducing the hands-on demands of ownership.

Explore Auben Realty

Table of Contents

Single Family vs Multifamily at a Glance

The two asset types reward different goals, and the gap shows up clearest when you line up cash flow, appreciation, and financing side by side.

  • Cash flow: Multifamily typically produces steadier monthly income because rent loss from one vacant unit is diluted across several others.
  • Appreciation: Single-family properties have historically tracked local home price trends more directly, while multifamily value is driven more by net operating income than by comparable sales.
  • Financing: A one-to-four-unit property qualifies for residential financing, while a five-plus-unit deal moves into commercial underwriting with different debt service coverage ratio (DSCR) and loan-to-value (LTV) requirements.
  • Entry cost: Single-family deals generally require less capital upfront than a multifamily acquisition of comparable total unit count.
  • Management: Multifamily concentrates repairs and tenant issues in one location, which can lower the time cost per unit once you have scale.
  • Liquidity: Single-family homes sell to a broader buyer pool, including owner-occupants, which tends to shorten exit timelines.

Starter investors and those who want a simple exit often gravitate toward single-family. Passive investors chasing stable monthly income, and operators ready to scale a portfolio, tend to lean multifamily.

How Returns Are Built: Cap Rates, Appreciation, and Loan Terms

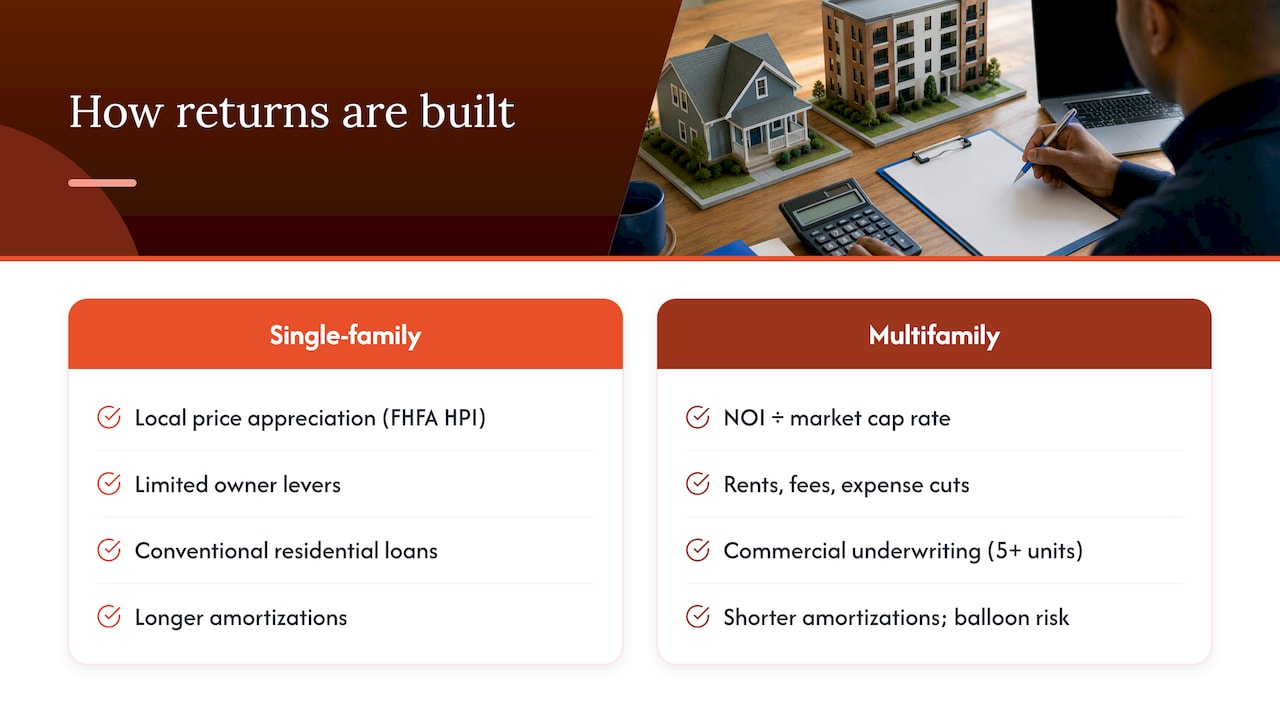
Multifamily value is a function of net operating income (NOI) divided by the market cap rate. Raise rents, add a laundry or parking fee, or cut operating expenses, and the resulting NOI increase flows straight into the property’s valuation. That’s why industry analysis points to multifamily as the asset class where owners can actively engineer value rather than wait on the market.

Single-family returns lean more heavily on local price appreciation. The FHFA House Price Index tracks single-family price changes using a repeat-sales method across all 50 states and more than 400 cities, and it remains the standard public benchmark for setting appreciation expectations in a given market.

Multifamily financing changed in 2025: the HUD Mortgagee Letter 2025-03 revised DSCR and LTV/LTC parameters for FHA-insured multifamily loans, adjustments aimed at improving financing access for qualified deals. One-to-four-unit properties still qualify for conventional residential loans with longer amortizations, while five-plus-unit deals face commercial underwriting, shorter amortization schedules, and sometimes balloon payments that create refinancing risk down the road. Both asset types allow depreciation deductions. Larger multifamily properties often present stronger opportunities for cost segregation studies that accelerate those deductions.

How Returns Are Built: Cap Rates, Appreciation, and Loan Terms — overview diagram

Managing Single-Family vs Multifamily Day to Day

Multifamily properties benefit from economies of scale: one roof, one parking lot, and one on-site maintenance stop can serve dozens of units, which lowers the per-door cost of upkeep. Single-family portfolios spread that same workload across multiple addresses, often multiple neighborhoods, which adds drive time and vendor coordination even though each individual repair tends to be smaller.

  • Multifamily concentrates tenant turnover, noise complaints, and maintenance requests in one place, which rewards an on-site or near-site manager.
  • Single-family spreads risk across locations, so a bad block or a problem tenant affects only one income stream rather than a cluster of units.
  • Capex lumpiness hits multifamily harder: a single failed roof or HVAC system can be a large one-time hit, while SFR repairs tend to stagger naturally across a portfolio.
  • Reserves should scale differently: budget heavier short-term capex reserves per building for multifamily, and per-property reserves that grow with your unit count for single-family.

A home management plan that spells out vendor response times and reserve targets makes the decision to self-manage or hire a property manager much clearer.

Pro Tip: Ask any property manager you’re interviewing how they handle a simultaneous repair across multiple units versus a single-property emergency; the answer tells you how they’ll actually run your portfolio.

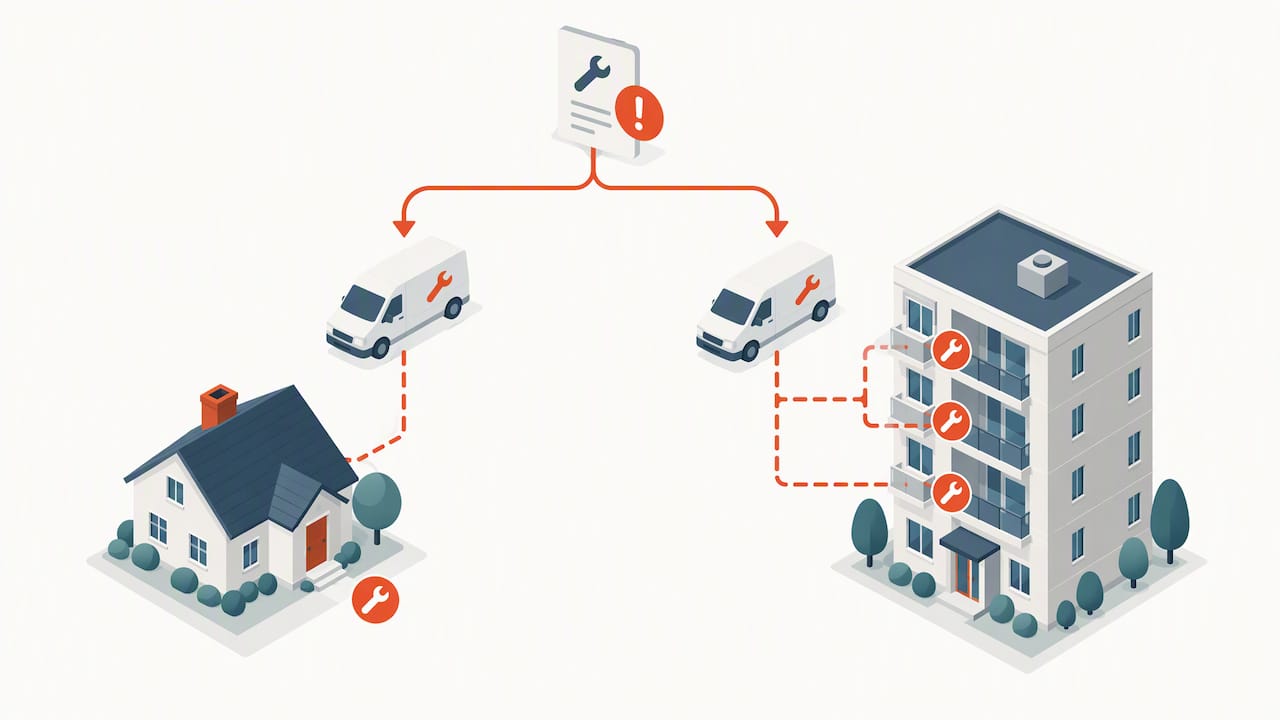
Illustration comparing property repair responses

Weighing the Risks, Reserves, and Exit Timing

Vacancy risk looks different across the two asset types. A vacant single-family rental means zero income until it’s filled, while a vacant unit in a ten-unit building still leaves nine streams flowing. Market cycles cut the other way too: single-family appreciation can swing with local demand, while multifamily income tends to hold steadier because leases are staggered.

  • Vacancy exposure: single-family is all-or-nothing; multifamily diversifies the loss across units.
  • Exit liquidity: single-family homes draw a wider buyer pool, including owner-occupants, which generally shortens resale timelines.
  • Buyer pool for multifamily skews toward investors, so pricing and timing depend more on cap rate trends and available commercial financing.
  • Contingencies worth building in: a capex reserve sized to your roof, HVAC, and major system ages, plus thorough due diligence on rent rolls before you bid.

A Practical Checklist for Choosing Your Asset Type

Run these steps before you commit capital to either path:

  1. Name your primary goal: cash flow, appreciation, portfolio scale, or hands-off passive income each points toward a different asset type.
  2. Run the cap rate against your financing cost: if the spread is thin after a rate hike, the deal may not support commercial debt service.
  3. Set a cash-on-cash target and test whether projected rents and expenses clear it before you factor in appreciation.
  4. Apply the DSCR test for any five-plus-unit deal, since lenders will underwrite to it regardless of your own return model.
  5. Scrutinize the comps: a multifamily valuation built on optimistic NOI projections, or a single-family comp set that ignores recent price softening, is a red flag.
  6. Ask your lender directly how the current DSCR and LTV thresholds affect your loan sizing before you tour a single property.
  7. Ask a property manager or broker what per-door costs and typical turnover look like in the specific submarket you’re targeting; tracking the key metrics investors should follow keeps this comparison honest.

Where Auben Realty Fits Into the Decision

We manage both single-family and multifamily portfolios across our markets, so we see the financing and operational differences play out on real deals, not just spreadsheets.

  • We offer asset management for investors scaling into multifamily and build-to-rent holdings.
  • We provide full property management for single-family and small multifamily owners who want hands-off operations.
  • Our multifamily and build-to-rent services support investors moving from single doors into larger holdings.
  • Our team uses a pod-based structure and in-house maintenance to keep per-door costs predictable.

An Editorial Take on Picking Your Lane

Go single-family first if liquidity and simplicity matter more than scale. Go multifamily first if you can clear the DSCR test and want income that doesn’t hinge on one tenant. Most serious portfolios end up hybrid eventually. Run the numbers on your specific deal, and talk to a property manager before you assume either path is easier than it looks.

— MediaBeast

Get a Clear Read on Your Next Property Move

We help investors figure out which asset type actually fits their numbers, then handle the work that comes after you buy. Whether you’re weighing a single-family rental against a small apartment building or ready to scale into multifamily and build-to-rent, our brokerage, property management, and asset management teams work from the same playbook you just read.

Aubenrealty

  • Request a free rental analysis to see what your property or target deal could realistically earn.
  • Talk through acquisition, renovation, and ongoing management with one team instead of three separate vendors.

Start with a free rental analysis and compare your options with real numbers.

FAQ

Is it better to buy single-family or multifamily?

Neither is universally better: single-family tends to suit investors who want liquidity, simpler financing, and appreciation tied to local home values. Multifamily tends to suit investors chasing steadier income and scale, once they can meet commercial DSCR and LTV requirements.

What is the 1% rule for multifamily?

The 1% rule is a quick screening test where monthly rent should equal roughly 1% of the purchase price for a deal to be worth deeper underwriting. It’s a rough filter, not a substitute for a full cap rate and NOI analysis on an actual multifamily deal.

Is it worth investing in multifamily?

Multifamily can be worth it for investors who want income diversified across several units and are prepared for commercial underwriting on five-plus-unit deals. Industry analysis points to improving multifamily income performance as net operating income growth has supported stronger valuations in recent years.

What is the difference between a single-family and a multifamily property?

A single-family property houses one rental unit on one lot, financed and sold like a typical home. A multifamily property contains two or more units; properties with five or more units shift from residential to commercial financing rules, including different DSCR and LTV standards.

How does scaling a rental portfolio typically work?

Investors often start with one or two single-family or small multifamily properties, then reinvest cash flow and equity gains into larger deals. A systematic approach to scaling a portfolio usually involves setting clear acquisition criteria before adding each new property.

Sources

Jacksonville Beach Rentals: $1,614 Avg and What Moves the Needle

The Jacksonville Beach rental market is stabilizing in 2026: average rents sit near $1,614 and demand is warm but cooling from recent spikes, which gives renters modest room to negotiate and tells owners to price new listings against real local comps rather than last year’s numbers.


TL;DR:

  • Rents are stabilizing around $1,614 with a small decline from recent peaks, giving renters negotiation power and emphasizing the importance of checking local comps.
  • Fewer new units are being built, which combined with steady demand from military, port, and seasonal workers, supports a modest rent increase by late 2026.
  • Neighborhood variation is significant, with coastal and downtown areas seeing higher demand and prices, while westside and northside offer more affordable options.
  • Renters should compare multiple listings and use the city’s code enforcement data before signing, while owners need to price based on current local comps and prepare units thoroughly.
  • Active management, local knowledge, and timing listings in late winter or early spring can improve leasing speed and rent performance in this balanced market.

Aubenrealty
Make Your Rental Work Harder
Auben Realty combines local market expertise with management, renovation, and tenant placement for owners and investors.

Explore Auben Realty

Table of Contents

What the Jacksonville rental market looks like right now

Average rent across the Jacksonville metro is about $1,614, and Zillow’s market summary labels the temperature “warm” with roughly 3,700 active rental listings and a small year-over-year dip in rent. That is a market with plenty of choice but not the frantic bidding seen in 2022 and 2023.

A few numbers frame where things stand:

  • Average rent: $1,614, per Zillow.
  • Active listings: roughly 3,744 units on the market at any given time.
  • Market temperature: warm, meaning demand is steady but not overheated.

Some aggregator sites peg the median closer to $1,699, a gap worth noting rather than ignoring. Different platforms pull from different listing pools, so treat the $1,614 figure as the benchmark and use any higher number you see elsewhere as a reminder to check multiple sources before signing or pricing a lease.

Why rents are moving the way they are

Two forces are pulling in opposite directions, and together they explain the calm. On the supply side, Colliers’ Q1 2026 multifamily report finds new unit deliveries slowing while occupancy stays healthy, a pattern Matthews’ Q2 2026 report confirms with measured stabilization after a multi-year construction boom.

The drivers worth tracking:

  • Supply contraction: fewer new units are breaking ground, which tends to firm up rents once the current pipeline is absorbed.
  • Demand sources: military relocations, port and logistics employment, and seasonal tourism all add renters without a single dominant driver.
  • Policy and transparency: the city’s new Stable Housing site and its Affordable Housing Dashboard give renters and owners access to code enforcement and eviction filing data that used to be hard to find.

Both Colliers and Matthews point toward modest rent growth returning by late 2026 as the construction slowdown works through the market, not a sharp spike.

Where rents and availability differ across neighborhoods

Jacksonville is large enough that averages hide real variation. Beach communities, downtown-adjacent areas, and suburban pockets each behave differently, and Realtor shows neighborhood medians spreading well above and below the metro figure.

Rough buckets renters and owners should know:

  • Jacksonville Beach and the coastal strip: tighter inventory, higher demand from short-term and seasonal renters, rents that run above the metro average.
  • Downtown and Riverside-adjacent areas: more new construction, which keeps availability higher and pricing closer to the metro median.
  • Suburban Southside and Mandarin: family-oriented inventory with steadier, less seasonal demand.
  • Westside and Northside: generally the most affordable pockets, often where new affordable housing projects are concentrated.

New below-market developments tracked on the city’s dashboard are adding supply specifically in a few of these pockets, which is worth checking before assuming a neighborhood is uniformly tight. For side-by-side comps, Auben Realty’s Jacksonville, FL listings page and the city’s own dashboard are both useful starting points.

What renters should expect when searching right now

A warm-but-calming market means listings move in weeks, not days, and landlords are more open to small concessions than they were two years ago, especially outside peak summer months.

A short checklist before you sign anything:

  1. Check the Stable Housing portal for code enforcement history or eviction filings tied to the address, using the data the city’s dashboard now makes public.
  2. Compare the listed rent against both Zillow’s $1,614 average and at least one other active listing in the same zip code.
  3. Ask about concessions such as a reduced deposit or a free week of rent, which landlords are more willing to offer when a unit has sat vacant past 30 days.
  4. Watch for red flags: vague maintenance language, no willingness to share an inspection report, or a landlord who will not provide a lease copy before a deposit.

Pro Tip: Searching in November or December typically means less competition and more room to negotiate than a summer move.

How owners should price and prepare a rental right now

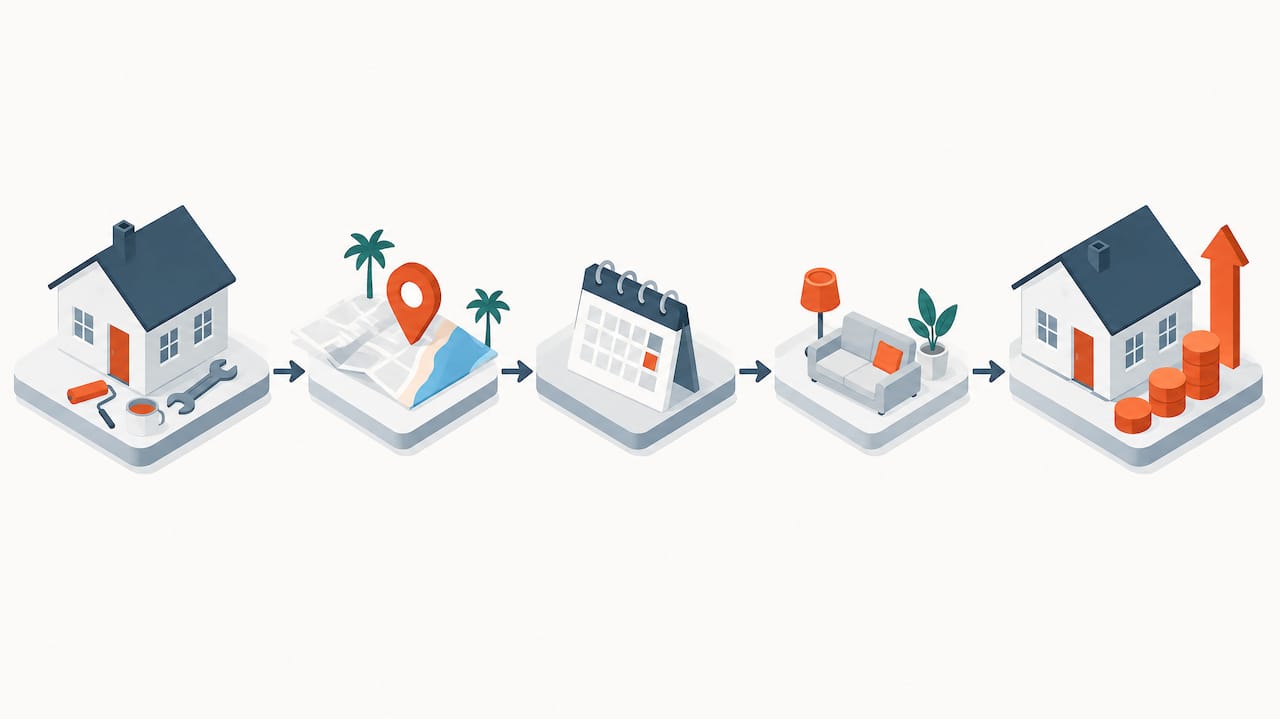
Rental pricing and preparation decision flow

Pricing a unit correctly the first time matters more in a stabilizing market than a hot one, because overpricing now means sitting vacant while comparable units lease around you.

Steps that keep a listing competitive:

  1. Pull comps from Zillow, Realtor.com, and active local listings, then adjust for condition, parking, and proximity to the beach or job centers.
  2. Run a rent-ready checklist: working smoke detectors, serviced HVAC, fresh paint, professional photos, and all required disclosures in order before the first showing.
  3. Time the listing: list in late winter or early spring ahead of peak summer demand, and reserve concessions for units that have been on the market more than three to four weeks rather than offering them upfront.
  4. Screen thoroughly: verify income and rental history, and keep screening criteria consistent with city fair housing guidance to avoid compliance issues.

Pro Tip: A small cosmetic refresh, like new light fixtures and a deep clean, often returns more in faster leasing than a rent increase returns in extra monthly income. Owners estimating renovation budgets before listing can also run numbers through a Jacksonville ARV calculator to check whether upgrades pencil out before committing.

What our local experience in Jacksonville tells us

Our End of 2025 Jacksonville Market Overview lines up closely with what Colliers and Matthews report for 2026: a market cooling from its pandemic-era peak but holding firm rather than falling.

What that experience looks like in practice:

  • We have managed rental property in Jacksonville for several years as part of a broader footprint of over 15 years in business and roughly 2,700 properties served across ten regional markets.
  • We have seen vacancy periods shrink by a week or more on units where owners accepted a modest, time-limited concession instead of holding firm on asking rent.
  • We have seen that units priced within a few percentage points of true local comps lease faster than units priced from outdated or national-average figures.

Our take on what actually moves the needle this year

Renters get the most value from checking the Stable Housing dashboard before signing, not from chasing the lowest listed rent. Owners get more from pricing against real local comps and leaning on professional management than from betting on a rent increase the data does not yet support. Everything else is secondary to those two moves right now.

— MediaBeast

How we help Jacksonville Beach owners price and fill rentals faster

Setting the right rent and keeping a unit occupied takes more than a glance at an average. We built our Jacksonville presence specifically to combine the kind of local comps and renovation know-how described above with full-service management, so owners do not have to track multiple reports themselves to get a confident number.

Aubenrealty

What that looks like day to day:

  • Property Management: ongoing leasing, rent collection, and maintenance coordination so owners stay hands-off.
  • Project Management: rent-ready renovation oversight before a unit ever hits the market.
  • Brokerage Services: support for owners who decide to buy or sell rather than hold.
Service What it covers
Property Management Tenant placement, rent collection, maintenance
Project Management Renovation oversight before listing
Asset Management Portfolio-level oversight for investors
Brokerage Services Buying and selling rental property

We have served properties across multiple regional markets over many years, including a growing presence in Jacksonville. If you own a rental here and want a number grounded in current local data rather than a national average, our property management team can walk through a rental analysis specific to your property and neighborhood.

FAQ

Is Jacksonville a good rental market right now?

Jacksonville is a reasonably favorable market for both renters and owners in 2026, with average rent near $1,614 and a “warm” rather than overheated temperature. Renters have more listings to choose from than in recent peak years, while owners still see healthy occupancy according to Colliers.

What is the current rental market situation in Florida?

Florida’s rental markets, including Jacksonville, are broadly moving from a recent period of rapid rent growth toward a steadier, more balanced pace. Jacksonville’s own data shows deliveries slowing and occupancy holding, a pattern consistent with the stabilization Matthews’ Q2 2026 report describes for the metro.

Is Jacksonville a buyer’s or seller’s market right now?

For rentals specifically, Jacksonville leans closer to balanced than firmly in either direction, with warm demand but enough active listings to give renters some leverage. Owners still benefit from pricing carefully against current comps rather than assuming continued rapid rent growth.

What are the best areas to rent in Jacksonville, Florida?

Jacksonville Beach and the coastal strip tend to command higher rents due to tighter inventory, while downtown-adjacent and suburban areas like Southside and Mandarin offer more availability closer to the metro average. Checking current listings on a local rentals page alongside the city’s housing dashboard gives a clearer neighborhood-by-neighborhood picture than relying on citywide averages alone.

Sources

Houston Cap Rates: Multifamily 5–6.5%, Industrial 5–6%, Auben’s Take

Houston cap rates currently span a wide band by sector: multifamily in a moderate range around 5 to 6.5%, industrial near 5% to 6%, retail somewhat higher, and office and hospitality generally higher still, with Class A CBD office cap rates recently exceeding 8% in some samples. Rates are drifting up on stabilized assets while compressing on well-located industrial. Before you act on any of these ranges, check your submarket and normalize the seller’s NOI with guidance on securing property insurance in Texas.


TL;DR:

  • Submarket conditions significantly impact cap rates, with industrial and retail ranges varying based on corridor-level rents and vacancy rates.
  • Class A assets typically trade at the lowest cap rates, while Class C and value-add deals often demand higher yields due to renovation and execution risks.
  • Concessions such as rent abatements and tenant improvements can overstate reported cap rates if not properly normalized in analysis.
  • A 7.5% cap rate in Houston generally indicates higher risk or value-add potential, while 5% suggests strong locations with rent growth expectations.
  • Careful due diligence, including adjusting for concessions and local fundamentals, is essential before relying on headline cap rate figures for investment decisions.

Aubenrealty
Make Your Houston Investment Work Smarter
Auben Realty combines local market expertise with investment-focused management, renovation, and tenant placement services for property owners and investors.

Visit Auben Realty

Table of Contents

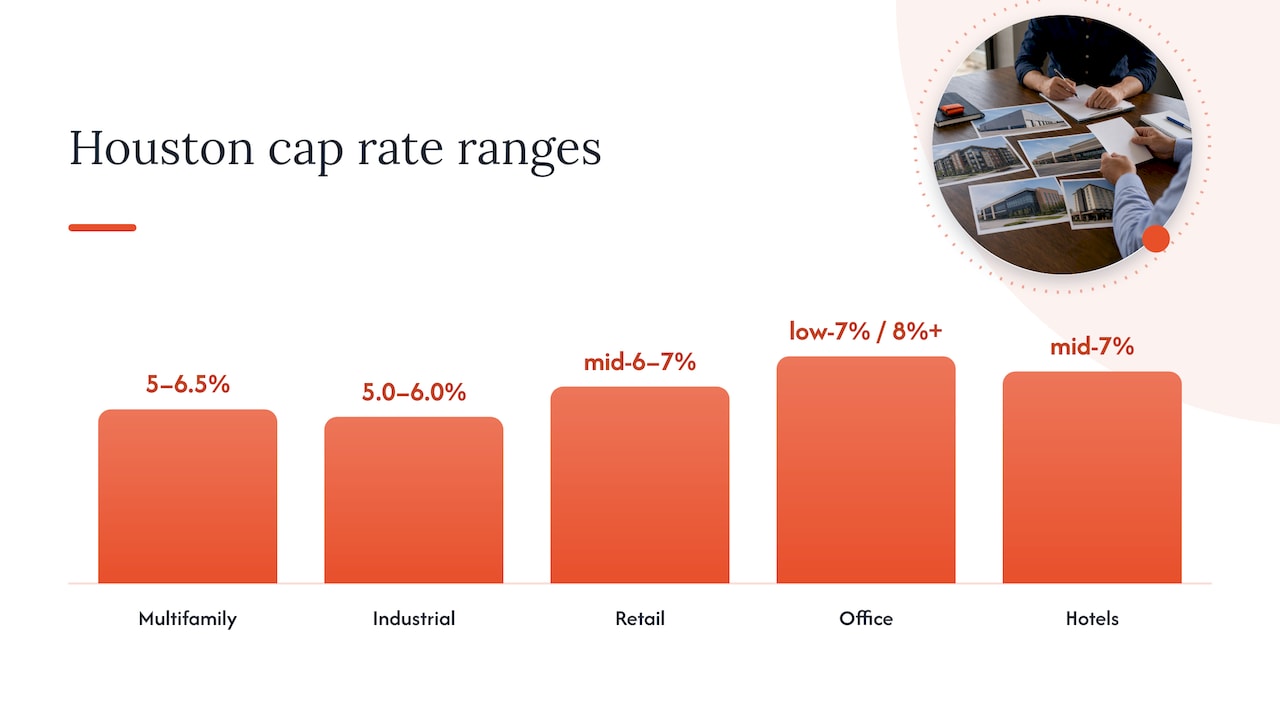
1. Current cap rates by sector in Houston

Every sector in Houston is telling a different story right now, and lumping them into one “market cap rate” hides the signal you need for underwriting.

Retail has drifted into the mid-6% to 7% range as some centers face re-tenanting risk, while office is the clear outlier.

IRR’s Mid-Year 2025 Viewpoint reported Class A CBD office cap rates rising above 8% in its sample, reflecting both genuine repricing and the broader national reset in office valuations. That same report documented a regional cycle shift favoring southern markets like Houston, which helps explain why capital kept flowing into multifamily and industrial even as office struggled.

  • Multifamily: mid-5% to 6.5%, with Class A near the bottom of that band and workforce housing near the top.
  • Industrial: 5.0% to 6.0%, among the tightest spreads in the metro.
  • Retail: mid-6% to 7%, wider for centers with anchor vacancy risk.
  • Office: low 7% for well-leased suburban product, 8%+ for CBD Class A per IRR’s sample.
  • Hotels: mid-7% range, reflecting higher operational risk and slower stabilization timelines.

Industrial direct asking rents and corridor-level vacancy data from Cresa’s Q3 2025 Houston industrial report show meaningful variation by corridor, and that variation is the main reason industrial cap rates differ so much from one submarket to the next even within the same broad sector range.

The extreme cases deserve a separate mention. Opportunistic buyers chasing workforce multifamily or value-add retail are underwriting entry yields well above these headline ranges, often 7% or higher, because they are pricing in renovation risk and lease-up uncertainty rather than in-place stabilized income. Treat any cap rate quoted without a class or condition qualifier as incomplete.

1. Current cap rates by sector in Houston — overview diagram

2. Submarket variation and asset-class nuance in Houston

A citywide cap-rate range is a starting point, not an answer. Houston’s submarkets move at different speeds, and the spread between a CBD asset and a suburban one in the same sector can run well over 100 basis points.

Industrial is the clearest example. Cresa’s Q3 2025 data shows direct asking rents and vacancy rates that diverge meaningfully across corridors, and those differences flow directly into cap rates. A fully leased building in a tight corridor with low vacancy commands a lower cap rate than a comparable building in a corridor carrying excess supply, even though both sit under the same “Houston industrial” headline. Investors comparing deals across corridors should pull comps from the same corridor whenever possible rather than relying on a metro-wide average.

Class distinctions matter just as much as geography:

  • Class A stabilized assets trade at the tightest cap rates because buyers are paying for in-place income with minimal lease-up risk.
  • Class B assets usually sit 25 to 75 basis points above Class A in the same submarket, reflecting older systems and more turnover.
  • Class C and value-add deals can price well above both, since buyers demand a higher entry yield to compensate for renovation costs and execution risk.
  • CBD office and retail generally carry wider cap-rate bands than suburban product right now, a direct result of the office repricing documented in IRR’s mid-year report.

For multifamily specifically, a stabilized suburban Class B property near strong job centers can price tighter than a CBD high-rise facing elevated office-adjacent vacancy, which runs counter to the old assumption that downtown always commands a premium. That shift is worth tracking if you are comparing acquisition targets across Houston’s diverse submarkets, where corridor-level fundamentals now matter more than general location prestige.

3. What’s moving Houston cap rates now: rents, vacancy, and financing

Three forces are driving the current spread in Houston cap rates, and two of them are easy to miss if you only look at a headline rate.

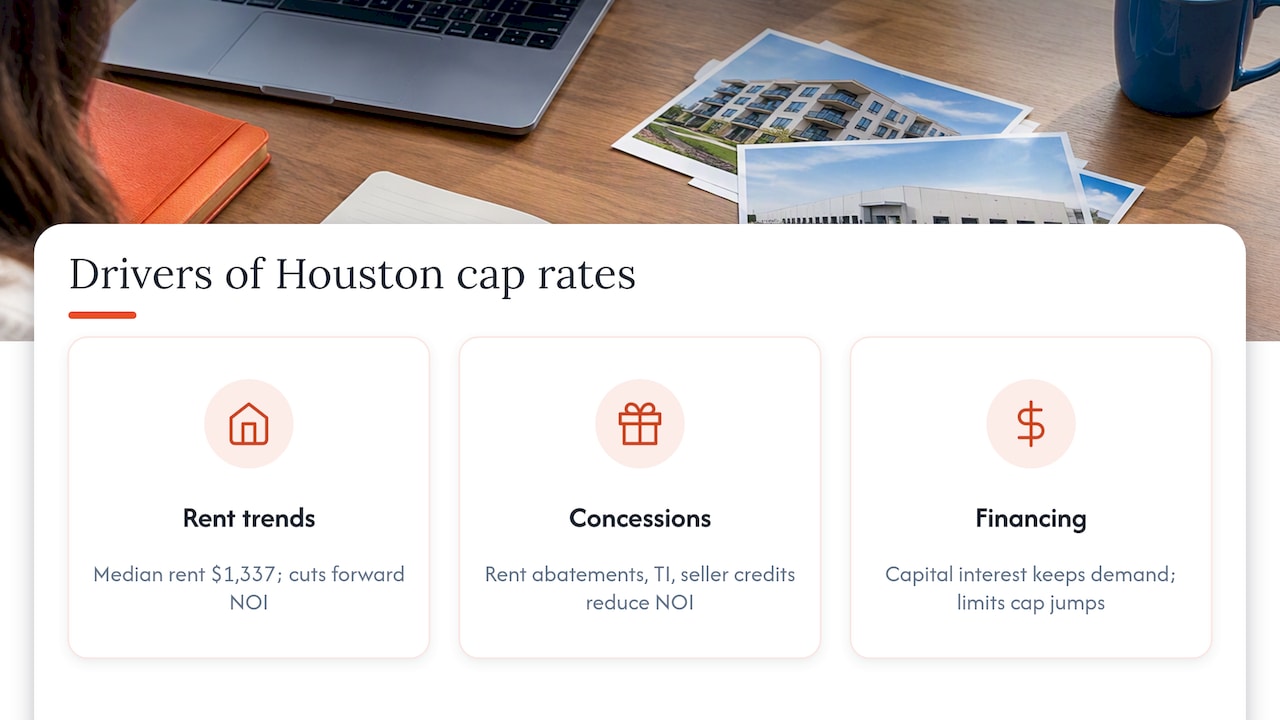
Three forces affecting Houston cap rates

Rent trends are the most direct driver. Realtor put the Houston metro’s median asking rent at around $1,337, down modestly year-over-year. Softer rent growth reduces forward NOI projections, which pushes buyers to demand higher cap rates on stabilized multifamily to hit the same return targets. At the same time, IRR’s mid-year report noted a regional cycle shift favoring southern markets, which has kept capital interested in Houston even as rent growth cooled.

The less obvious driver is concessions. Reporting from GlobeSt in March 2026 documented how sellers are increasingly using rent abatements, larger tenant improvement allowances, and seller-financed credits to keep a deal’s headline price and reported cap rate looking stable, even when the underlying asset has repriced. A seller offering six months of free rent on a new lease, for example, is effectively discounting the deal while keeping the face rent and the reported cap rate unchanged on paper.

This matters because a transactional cap rate built on concession-heavy leases overstates the true in-place yield. If you underwrite the headline number without adjusting for the concession package, you are paying for income that will not materialize once those concessions roll off.

Pro Tip: Convert any large TI allowance or rent abatement into an annualized expense over the lease term, then recalculate the cap rate on that adjusted NOI before you compare it to another deal.

4. How to use cap rates in underwriting: a step-by-step checklist

Treat the reported cap rate as a starting point for your own analysis, not a conclusion. Here is a practical sequence for any Houston acquisition:

  1. Verify trailing twelve-month NOI against the rent roll and expense statements rather than relying on a broker’s pro forma.
  2. Strip out and re-add concessions such as free rent, TI allowances, and seller credits as annualized adjustments, per the method GlobeSt’s reporting on concession practices points to.
  3. Compare the adjusted cap rate to submarket comps, using corridor-level or neighborhood-level data rather than a metro average.
  4. Run a sensitivity test on exit cap rate assumptions, since even a 50 to 100 basis point shift can materially change your projected return.
  5. Model at least two financing scenarios, since rate movement changes the spread between your cap rate and your cost of debt.
  6. Check vacancy and rent trend direction for the specific submarket, using current data such as Realtor, since a declining rent environment erodes forward NOI faster than most pro formas assume.

That is the kind of swing a half-point of cap-rate movement produces, and it is why exit assumptions deserve as much scrutiny as entry pricing.

Watch for these red flags in any marketing package: a cap rate calculated on a pro forma rent roll rather than trailing actuals, concessions buried in a footnote instead of the NOI line, and a cap rate that does not disclose whether it reflects a transaction price or an asking price.

6. Auben Realty’s on-the-ground perspective on effective yield

With many years managing investment properties and numerous properties served across our regional markets, we see the gap between a reported cap rate and the yield an owner actually realizes play out constantly. A property’s effective cap rate is shaped far more by execution than by the number on the offering memo.

The cap rate you underwrite and the cap rate you realize align only if nothing changes in how the property is managed.

Renovation sequencing, lease-up pacing, tenant placement quality, and expense control can all shift NOI after closing, sometimes more than the acquisition price does. Properties bought at the higher end of reported cap rates can sometimes perform better if management improves operations quickly.

Pro Tip: Budget for lease-up and renovation timelines separately from your stabilized cap rate assumption. Underwriting both at once overstates year-one returns.

7. Where the real risk sits for Houston investors right now

The biggest mistake I see is treating a headline cap rate as a finished analysis instead of a starting point that still needs adjusting for concessions, submarket fundamentals, and financing terms. Houston’s upside is real: industrial corridors remain tight and multifamily demand is resilient even with softer rent growth. The risk is paying a stabilized-asset price for a deal that is quietly discounted through concessions you did not strip out.

My direct recommendation: run the full underwriting checklist above on any letter of intent within 48 hours of receiving it, before emotional attachment to the deal sets in.

— MediaBeast

How Auben Realty supports cap-rate due diligence in Houston

Once you have a cap rate you trust, the next question is who closes the gap between projected and realized returns. That is where our Houston property management services come in: handling lease-up, tenant placement, and expense control so the NOI you underwrote has a real path to showing up on the rent roll.

Aubenrealty

For investors weighing an acquisition, our asset management services provide ongoing oversight of performance against your underwriting assumptions, and our brokerage services can help source and structure deals across our Houston market. If you are weighing a renovation-heavy value-add play, project management support keeps that work on schedule and on budget. Reach out through our Houston page to talk through a specific deal.

FAQ

What is a 7.5% cap rate?

In Houston’s current market, that level sits above typical stabilized multifamily and industrial pricing but within range for hotels and some value-add retail or workforce housing deals.

Are rents going down in Houston?

Houston metro median asking rent was $1,337 in September 2025, down about 3.0% year-over-year, according to Realtor.com’s rental report. That decline has pressured forward NOI projections on multifamily deals and is one reason buyers are demanding higher cap rates on some stabilized assets.

Is 7% a good cap rate?

Compare it to recent transaction comps in the same corridor and asset class rather than treating it as a universal benchmark.

Is 5% a good cap rate?

A 5% entry yield generally signals a premium location or asset with strong rent growth expectations baked into the price, so it warrants extra scrutiny of the underlying NOI assumptions.

Sources

The ranges in this article draw from a mix of broker market reports, an industry research firm’s mid-year local report, and metro rent data, covering roughly the second quarter of 2025 through the first quarter of 2026. Different providers calculate cap rates differently: some report transaction-based caps from closed sales, while others report caps implied by current asking prices, which tend to run softer than actual trades.

Refresh these figures quarterly, since rent and vacancy data update faster than transaction-based cap-rate surveys.

Estimate Jacksonville Property Tax in Minutes With Duval’s Estimator

There is no single Jacksonville property tax rate. Your actual bill depends on the combined millage for your specific taxing district, which stacks county, city, school, and special district rates together. The Duval County Property Appraiser and the county’s tax estimator are where you find your parcel’s real number, and your TRIM notice plus any homestead exemption or Save Our Homes cap determine what you actually owe.


TL;DR:

  • Your actual property tax depends on the combined millage rates of county, city, school, and special districts, which vary by location.
  • The property tax bill is calculated by stacking multiple mills, meaning two similar homes nearby can have different taxes.
  • Use Duval County’s tools and your TRIM notice to accurately estimate your bill, rather than relying on generalized online rates.
  • Confirm actual rates and exemptions through the Property Appraiser or Tax Collector offices rather than assumptions based on averages.
  • Homestead exemptions can reduce your tax bill significantly, especially if you qualify for the Save Our Homes cap.

Aubenrealty
Make Property Ownership More Manageable
Auben Realty combines property management, renovation, and tenant placement to help owners reduce hands-on involvement.

Explore Auben Realty

Table of Contents

Why a single Jacksonville tax rate figure can mislead you

A “mill” equals $1 of tax for every $1,000 of taxable value, and your final bill is the sum of several mills layered on top of each other rather than one flat percentage. That is why two houses a few blocks apart can carry different totals even with similar market values.

Your parcel’s millage typically combines:

  • County government: the base rate covering countywide services like public safety and general operations.
  • City of Jacksonville: municipal services for properties inside city limits.
  • Duval County Public Schools: a significant share of most bills, set separately from city and county rates.
  • Special districts (MSTUs): added charges for things like fire protection or specific improvement districts that only apply within defined boundaries.

Because these layers vary by location, the only way to know your real number is to check the current millage schedule for your specific taxing district, which the Property Appraiser publishes and updates alongside historical rates. Your annual TRIM notice lists the exact authorities taxing your parcel and the proposed rate for each one.

How to estimate your bill with Duval County’s tools and TRIM data

Running your own estimate takes a few minutes if you work through it in order.

  1. Search for the parcel on the Property Tax Estimator, either by address or by selecting the municipality if you are evaluating a hypothetical purchase.
  2. Enter the expected purchase price rather than the current assessed value, since a sale typically resets taxable value for the new owner.
  3. Indicate homestead status, and include portability information if you are transferring a Save Our Homes benefit from a prior Florida homestead.
  4. Cross-check the result against your TRIM notice or the published millage schedule for that taxing district to confirm the authorities and rates the estimator used.
  5. Treat the output as a planning number, not a guarantee, since the tool itself states its results are estimates built from the latest available tax roll rather than a final bill.

The Property Tax Estimator is built for scenario analysis, and the final certified roll along with adopted millage rates after the TRIM process are what actually bind your bill. Numbers can shift between the estimate you run today and the rate the taxing authorities formally adopt later in the year.

Pro Tip: Run the estimator twice, once with homestead assumptions and once without, so you see the full range before you commit to a purchase price.

Two property tax estimate paths compared

Where to get official rates and help in Duval County

When your estimate raises questions, Duval County has distinct offices for valuation issues versus payment issues, and knowing which one to call saves time.

  • Duval County Property Appraiser publishes millage schedules, parcel values, TRIM notices, and exemption forms, making it the first stop for valuation or exemption questions.
  • Duval County Tax Collector – Yates Branch (downtown) handles in-person payments and receipts from a central location with high foot traffic.
  • Duval County Tax Collector – Roosevelt Branch offers the same payment and receipt services for residents on that side of the county.
  • Duval County Tax Collector – Mandarin Branch covers payment processing for the Mandarin area, reducing the need to travel downtown.
  • Income Tax Office is a branch-level location providing payment assistance for residents in its immediate service area, functioning similarly to the other Tax Collector branches rather than handling valuation questions.
Office Role Google reviews
Duval County Tax Collector — Yates Branch (downtown) Payments, receipts, in-person taxpayer assistance 4.6★
Duval County Tax Collector – Roosevelt Branch Payments, receipts 4.5★
Duval County Tax Collector – Mandarin Branch Payments, receipts 4.3★
Duval County Property Appraiser Millage schedules, valuations, exemptions, TRIM notices 4.4★ (51 reviews)
Income Tax Office Local branch payment assistance 3.6★ (16 reviews)

For valuation disputes or exemption questions, contact the Property Appraiser directly. For a payment that is due or a receipt you need, any Tax Collector branch, including the Income Tax Office location, can help.

Prioritize parcel data over generalized rates

The TRIM notice and the county’s own tools beat any generalized rate you find online, because only they reflect your parcel’s actual taxing districts and proposed millage. When a number does not match what you expected, call the Property Appraiser for valuation questions or a Tax Collector branch for payment questions rather than guessing. Serious investors build this verification step into acquisition modeling before a purchase price is finalized.

— MediaBeast

Auben Realty: tax-aware support for Jacksonville investors

We help investors translate Jacksonville’s parcel-specific tax mechanics into real acquisition and ownership numbers, rather than leaving that work to a generic estimate.

Aubenrealty

Our asset management service builds tax scenarios into underwriting before you commit to a purchase price, and our property management team keeps ongoing tax obligations factored into your operating budget. For owners weighing renovation decisions that could affect assessed value, our project management service keeps that work coordinated.

  • We consider tax scenarios during underwriting.
  • We coordinate renovation and tenant placement to help keep ownership low-effort.

If you are evaluating a Jacksonville property and want help building a realistic tax picture into your numbers, start with our Multifamily & Build-to-Rent Services page or reach out through Property Management to talk through your specific parcel.

FAQ

How much is property tax in Jacksonville?

There is no flat citywide figure. Your bill depends on the combined millage for your parcel’s taxing district, which you can estimate using the Duval County Property Appraiser’s tools and confirm against your TRIM notice.

What is the property tax rate in Overland Park, KS?

Overland Park sits in Johnson County, Kansas, which uses a different assessment and mill levy system than Duval County, Florida. Residents there should check with Johnson County’s own appraiser and treasurer offices rather than applying Jacksonville figures, since the two states calculate taxable value differently.

What city has the highest property taxes in Florida?

Florida property tax totals vary by county and by the specific taxing districts layered onto each parcel, so no single city holds a fixed statewide ranking. The most reliable way to compare is checking each county property appraiser’s published millage schedule directly.

What city in Kansas has the lowest property tax?

Property tax totals in Kansas vary by county and taxing district in the same way Florida’s do, so pinpointing one city requires checking county-level mill levy data rather than relying on a statewide average. Readers researching Kansas rates should consult the relevant county appraiser’s office for parcel-specific figures.

Does homestead exemption lower my Jacksonville tax bill?

Yes. Florida’s homestead exemption can reduce taxable value significantly for qualifying owners, and the Save Our Homes provision limits how much your assessed value can increase each year once you hold the homestead.

Sources

Avoid $4,000 Turnover: 90–120 Day Lease Renewal Strategy for Landlords

Start renewals earlier and fix maintenance before offers go out. That single change raises retention more than any price cut, because tenants who feel heard and see a clean unit report tend to stop shopping around. Pair early outreach with a pre-renewal inspection and outcome-based incentives, and keep your timeline predictable. Managed programs build this sequence into every portfolio.


TL;DR:

  • Conduct renewal outreach between 90 and 120 days before lease end to gauge tenant sentiment early and avoid rushed, emotional decisions.
  • Use a structured timeline with dual deadlines at 120 days and 45 days to improve retention and ensure timely renewal or marketing.
  • Focus on outcome-based incentives, such as rent credits or policy changes, instead of blanket rent discounts to protect long-term profitability.
  • Prioritize maintenance responsiveness and document inspections thoroughly to influence renewal decisions and mitigate disputes.
  • Start renewal processes early, leverage market comps accurately, and assess tenant payment history to make informed, risk-aware renewal offers.

Aubenrealty
aubenrealty.com
Make Lease Renewals Less Hands On
Auben Realty combines property management, tenant placement, and local market expertise to help owners manage renewals and protect property value.

Visit Auben Realty

Table of Contents

A renewal timeline that keeps you ahead of move-out decisions

Two deadlines work better than one. An early soft check, placed 90 to 120 days before lease end, lets you gauge sentiment before a tenant starts browsing listings. Large operators who move renewal conversations to the 120-day mark report better retention because tenants make fewer rushed, emotional choices. A second, firmer deadline at 45 to 60 days then triggers your operational fallback: marketing the unit if the tenant has not responded.

A typical sequence looks like this:

  1. 120 to 90 days out: Pull market comps, schedule the pre-renewal inspection, and send a soft-touch message asking about renewal intent.
  2. 90 to 75 days out: Complete the inspection, open any repair work orders, and finalize the rent figure.
  3. 75 to 60 days out: Send the formal renewal offer with term options and any incentive language.
  4. 60 to 45 days out: Follow up by phone or text if there is no response; treat the 45-day mark as the hard deadline for a decision.
  5. 45 to 30 days out: Execute the signed renewal or begin listing the unit if the tenant has declined.

Assign roles so nothing stalls at a handoff: leasing staff own the outreach and offer language, maintenance owns inspection follow-through, and whoever runs your CRM owns the reminder cadence. A few checkpoints keep the process honest:

  • Leasing confirms comps and drafts the offer before day 75.
  • Maintenance closes every inspection-triggered work order before the offer goes out.
  • Marketing or CRM staff log every tenant touchpoint so a stalled renewal is visible, not forgotten.

Setting renewal rent without pricing out a good tenant

Pull comps on units with matching size, floor level, and amenity access, then adjust for any concessions those comps are currently offering. A unit with a one-month free promotion two floors down is not a clean comparison until you normalize for that discount.

Push higher when your market has clearly inverted toward landlords, or when the unit needed no repairs and the tenant has a thin payment history. Undershoot it, or hold flat, when the tenant has a strong record, the unit needs work you have not finished, or your comps show flat to falling asking rents nearby.

Offering multiple term lengths, commonly 12, 18, and 24 months, gives tenants flexibility and gives you a lever besides price. A tenant anxious about a larger jump might take an 18-month term at a smaller annual increase, which locks in occupancy longer than a standard 12-month renewal would.

Average unit turnover costs run around $4,000 per unit, according to industry estimates cited by the National Apartment Association, which is the number that should anchor every pricing decision: a modest rent concession almost always costs less than a vacancy.

Building renewal incentives that do not erode your returns

Blanket free-rent offers feel generous but they set a precedent and cost cash flow immediately. Outcome-based incentives, tied to a longer lease term or an early signature, protect net operating income while still giving tenants a reason to commit. Operators have found that value-add incentives and policy changes often outperform temporary financial concessions for long-term retention.

Strong incentive options include:

  • A rent credit applied only after the tenant signs a 24-month term, not before.
  • A pet-policy change or reduced pet deposit, which can matter more to a tenant than a small rent reduction.
  • A priority-repair guarantee, such as a 48-hour response window, written into the renewal offer.
  • A referral credit if the tenant brings in a qualified applicant for another vacant unit.

Loosening pet restrictions in particular can be a higher-impact retention lever than a short-term rent concession, since pet-owning tenants often struggle to find comparable housing and will pay to avoid moving. When you do offer a temporary financial concession, attach a condition: a credit that applies only if the tenant completes the full new term protects you from subsidizing a tenant who leaves early anyway.

Pro Tip: Offer the incentive in the same message as the rent figure, never as a separate follow-up; tenants respond better when the full picture arrives at once.

Operations that keep tenants from starting to look elsewhere

Maintenance responsiveness is the operational lever most likely to decide a renewal before pricing ever enters the conversation. Centralized, timely maintenance response is widely cited as the top factor behind non-renewal when it is absent. Close out open tickets before the renewal offer goes out, and treat any inspection-triggered repair as a priority rather than routine backlog.

A simple communication cadence supports this: a text-first outreach for routine updates, portal confirmations for anything requiring a signature, and a phone follow-up if 10 days pass with no response. Automated CRM nudges can carry a meaningful share of this load. Portfolios using renewal automation have reported roughly a 6% lift in renewal rates compared with manual outreach alone. Recurring plumbing issues are a common trigger for complaints during this window, and preventive attention to common failure points before the renewal cycle starts can head off a bad inspection.

Track a short list of operational KPIs:

  • Average repair turnaround time from ticket to close.
  • Response rate to renewal offers within the first 10 days.
  • Percentage of follow-ups completed on schedule.

Personalizing the renewal letter itself matters too: referencing a tenant’s specific maintenance history or service record increases renewal likelihood more than a generic notice does. For a deeper breakdown of maintenance categories and response planning, see this guide to the three kinds of maintenance your property will need.

Courts increasingly expect a documented trail, not a verbal agreement, when a renewal or rent increase is contested. Pre-renewal inspections, proof-of-service for rent increases, and signed tenant acknowledgments are the records most likely to matter if a dispute reaches a hearing.

  1. Schedule the pre-renewal inspection 30 to 60 days before the lease ends, using a short checklist covering five core areas: appliances, plumbing, HVAC, safety devices, and general wear.
  2. Photograph every item on the checklist, pass or fail, and attach the photos to the tenant’s file.
  3. If the inspection finds an issue, open a work order immediately and confirm completion before the renewal offer goes out.
  4. Serve any rent-increase notice as a separate document from the renewal offer itself, and keep proof of delivery, whether that is a signed receipt, a portal timestamp, or certified mail.
  5. Collect a tenant acknowledgment of the new terms, even informally, alongside the signed lease.

Keep the completed inspection record, the rent-increase notice with its proof of service, and the signed renewal in the tenant’s digital file for at least the length of the new lease term plus one year. A short, consistently completed checklist holds up better across a portfolio than a long form that staff skip under deadline pressure.

Measuring whether your renewal strategy is actually working

Four numbers tell you most of what you need: renewal rate, net effective rent change after incentives, turnover cost per unit, and average days to re-rent a vacated unit.

Run a simple comparison before approving any concession. Say a unit renting for $1,500 a month would cost $4,000 to turn, based on commonly cited industry turnover estimates, once you account for vacancy, marketing, and make-ready work. A $75-a-month concession over a 12-month renewal costs $900, far less than the turnover cost, which makes the concession the cheaper option whenever a tenant is genuinely on the fence.

  • Review renewal dashboards weekly during peak leasing season.
  • Run a cohort analysis quarterly to see how renewal rates move with pricing changes.
  • Flag any unit with declining renewal interest for an early inspection, not just an early offer.

Renewal rates have been rising across several industry datasets even as rent growth has cooled, which suggests retention is becoming a more reliable lever than chasing new tenants at market rate.

Handling tenants who go quiet or push back during renewal

A non-responsive tenant is not automatically a lost renewal, but silence past your soft-check deadline should trigger a specific sequence rather than repeated identical emails. Switch channels: if the first outreach was a portal message, follow with a text, then a phone call, spacing each attempt by a few days rather than stacking them.

Tenant renewal outreach sequence timeline

When a tenant does respond but pushes back hard on price or terms, resist matching their counter immediately. Ask what specifically is driving the objection: a competing offer, a budget change, or dissatisfaction with maintenance history. A tenant upset about slow repairs responds better to a service guarantee than to a rent discount, while a tenant citing a cheaper comp elsewhere needs a term-length or incentive conversation, not a bidding war.

Document every difficult interaction the same way you document a standard renewal: date, channel, and outcome. If a tenant remains unresponsive past your hard deadline, treat that date as final and begin marketing the unit immediately rather than holding it open indefinitely on the chance of a late reply. Holding a unit past the hard deadline without action is one of the most common ways renewal timelines quietly collapse into longer vacancies.

For tenants who are difficult but ultimately valuable, a short phone call from a manager, rather than a leasing agent, can resolve friction that email cannot. The goal is not to win every negotiation but to close the loop fast enough that you still have time to re-lease if the renewal falls through.

How market cycles should change your renewal approach

A tight rental market with falling vacancy supports firmer pricing and shorter negotiation windows, since tenants have fewer comparable options to shop against. A softer market, where comparable units are offering concessions, calls for more flexibility on term length and incentive structure before you touch the base rent.

Renewal rates have stayed resilient even as rent growth has slowed in recent data, which points to a broader shift: landlords increasingly treat renewals as the more dependable path to stable occupancy, rather than a fallback when new leasing is slow. That shift matters most in a cooling market, where the cost of chasing a new tenant at a marginally higher rent can easily exceed the cost of renewing an existing one at a smaller increase.

Watch your local comps closely during any rate or employment shift, since renewal pricing that made sense six months ago can become a retention risk quickly if nearby concessions change. In a rising-rate environment, tenants also weigh moving costs more heavily, which gives landlords slightly more room to hold firm on price, but that room shrinks fast once multiple nearby properties start offering free months or reduced deposits. The practical response is the same in either direction: price from current comps, not last quarter’s, and revisit your incentive mix every leasing season rather than setting it once a year.

How market cycles should change your renewal approach — overview diagram

Reading tenant financial stability before you commit to a renewal

A renewal decision is also a credit decision, even though it rarely gets treated that way. Payment history over the current lease term is the strongest signal you have: a tenant who paid on time for 11 of 12 months carries far less risk than one with several late payments clustered near the end of the term, even if both ultimately paid in full.

Look beyond the ledger when you can. A tenant who has mentioned a job change, a reduced work schedule, or a new dependent in maintenance requests or communications is worth a direct, low-pressure conversation before you finalize an offer. This is not about re-running a full credit check at every renewal, which is rarely necessary or practical, but about weighing the information you already have.

Where risk looks elevated, a shorter renewal term, a smaller rent increase, or a request for updated income verification can protect you without forcing a non-renewal. Where a tenant’s record is strong, that same information supports offering better terms, since retaining a reliable payer at a modest increase is almost always better than testing the market with an unknown applicant.

Auben Realty’s applied take on running renewal programs

Across managed portfolios, renewal timelines are built around early outreach, inspection-first risk review, and outcome-based incentives rather than flat concessions. A pod-based team structure keeps leasing, maintenance, and resident communication tied to the same renewal calendar, and in-house maintenance means repair work from an inspection does not wait on a third-party vendor’s schedule. Owners working with a managed renewal program should expect fewer surprise vacancies and a documented trail for every rent increase and inspection.

— MediaBeast

How Auben Realty can help with your renewal program

Running a 90-day timeline, an inspection checklist, and incentive tracking across dozens of units takes staff time most owners do not have. Auben Realty’s property management services build that calendar into day-to-day operations, while project management support handles any unit upgrades a renewal negotiation calls for, and asset management reporting shows portfolio-level renewal performance. Owners who want a managed renewal process can start with a consultation through our property management page.

Aubenrealty

FAQ

How do you negotiate a lower rent renewal?

Point to specific, verifiable comps for comparable units nearby and ask the landlord to match or adjust based on that data rather than making a general affordability argument. Offering a longer lease term in exchange for a smaller increase is also a common and effective trade for both sides.

What should you avoid saying during a renewal negotiation?

Avoid vague threats to move without a real plan, since landlords can usually tell when a tenant is bluffing and it weakens your position in future conversations. Also avoid oversharing financial hardship details that are not directly relevant to the lease terms being discussed.

What are the pros and cons of renewing a lease?

Renewing avoids the cost and disruption of moving and keeps a known, stable arrangement in place for both parties, while a new lease elsewhere might offer a lower rent or better amenities. The main downside of renewing is the risk of accepting a rent increase without fully checking whether better terms exist nearby.

What tactics work best when negotiating a lease?

Come with current market comps rather than a general request for a discount, and ask for flexibility on term length if the rent figure itself will not move. Landlords are also more likely to negotiate on non-financial terms, such as a maintenance guarantee or a pet-policy exception, than on the base rent alone.

How early should a landlord start the lease renewal process?

Most guidance points to starting 90 to 120 days before lease end, which gives tenants time to decide without feeling rushed. Large operators have found that moving renewal conversations to the 120-day mark improves retention compared with the standard 60 to 90 day window.

Sources

Protect Your Refinance Exit: BRRRR and IRS Essentials for U.S. Investors

BRRRR stands for Buy, Rehab, Rent, Refinance, Repeat, a capital-recycling strategy that lets investors convert one property into the funding for the next when rehab and refinance go to plan. It suits investors with access to renovation capital, contractor relationships, and a realistic refinance exit. The main risks are rehab overruns, refinance seasoning delays, and the temporary cash tied up between purchase and payoff.


TL;DR:

  • BRRRR deals are highly sensitive to rehab overruns, refinancing delays, and the property’s appraisal coming in lower than the projected after-repair value.
  • Successful deals require buying undervalued properties with a wide margin between purchase price and ARV, especially in stable or growing neighborhoods.
  • Proper underwriting involves a strict 70% rule based on ARV minus repair costs, along with thorough due diligence on property condition and local rental demand.
  • Refinance seasoning rules and lender requirements for lease signing and documentation are critical factors that influence timely capital recovery.
  • Running conservative stress tests that account for higher rehab costs, longer vacancy, and lower ARV helps identify deals with real profit margins.

Aubenrealty
Build A More Manageable Investment
Auben Realty helps investors manage properties, renovations, and tenant placement with local expertise and less hands-on involvement.

Explore Auben Realty

Table of Contents

How to find and underwrite BRRRR-appropriate deals

The buy phase decides whether the entire cycle works. You want distressed or undervalued properties where the gap between purchase price and after-repair value (ARV) is wide enough to cover rehab costs, financing costs, and still leave equity on the table. Neighborhood fundamentals matter as much as the house itself: stable or growing rent demand, low vacancy, and a realistic buyer or appraiser pool for comparables.

Most investors underwrite with a version of the 70% rule: offer no more than 70% of ARV minus repair costs. It is a screening tool, not a guarantee, since financing costs, closing costs, and holding costs also eat into margin. Pair it with projected post-rehab rent and cap rate to confirm the deal cash flows once it is refinanced, not just once it is rented.

Financing at purchase shapes your exit. Cash and hard-money loans give you speed and negotiating power on distressed properties, while bridge loans can fund both purchase and rehab in one draw structure. Whichever you choose, know your refinance lender’s seasoning rules before you close, since that timeline determines how long you are carrying short-term financing costs.

Before making an offer, run through a due diligence checklist:

  • Pull a title search to confirm there are no liens or ownership disputes.
  • Get a full property inspection, including roof, foundation, and major systems.
  • Verify permit history for any prior additions or conversions.
  • Check at least three to five recent comparable sales for ARV accuracy.
  • Research local rental demand through vacancy rates and comparable listings.

A free rental analysis can help confirm rent expectations and tenant demand before you commit capital to a deal.

Rehab: budgeting, contractors, and keeping scope under control

Not every renovation dollar moves ARV or rent equally. Kitchens, bathrooms, and major mechanical systems (HVAC, electrical, plumbing) tend to drive the most value per dollar spent, followed by curb appeal items like paint, landscaping, and entry doors. Cosmetic upgrades beyond that point often cost more than they return.

Build your rehab budget in four parts: hard costs (materials and labor), soft costs (permits, design, inspections), a contingency reserve, and financing or holding costs for the rehab period.

Vet contractors on past work, licensing, and insurance, then lock in a fixed-bid scope of work rather than open-ended time and materials. Structure payment as a draw schedule tied to completed milestones, and require signed lien waivers at each draw to protect your title.

  • Get at least three competing bids before awarding the rehab contract.
  • Put the scope of work in writing, including materials, brands, and finish levels.
  • Require lien waivers with every draw payment.
  • Build a punch list before the final draw releases.

Pro Tip: Walk the property with your contractor before writing the scope of work. Verbal assumptions are the most common source of change orders.

Surprises tend to hide behind walls and under floors. A short pre-rehab checklist covering sewer scope, electrical panel capacity, and moisture readings can catch expensive issues before they become mid-project change orders. Our best renovations guide breaks down which upgrades reliably pay off in rent and resale value.

Inspector checking rental home electrical panel

Rent: getting to a signed lease the refinance will accept

Stabilization is where BRRRR deals either support a strong appraisal or stall. Lenders want to see occupied, cash-flowing property with documentation to prove it, so pricing and screening speed both matter.

  1. Set rent using at least three current comparable listings in the immediate area, not citywide averages, and build in a modest vacancy assumption.
  2. Screen tenants on income, credit, rental history, and background checks, and use lease clauses lenders commonly expect, like clear term length and renewal terms.
  3. Time the lease signing with your refinance seasoning window in mind. Some lenders require a signed lease in place before underwriting will proceed.
  4. Assemble a documentation pack as you go: the signed lease, dated photos of the finished unit, and paid rehab invoices.

Having this pack ready before you apply shortens the refinance timeline considerably.

Refinance: recovering your capital without the appraisal surprise

The refinance is the step that actually returns your cash, and it is also where most BRRRR plans break down. Investors generally choose between DSCR (debt-service coverage ratio) loans, conventional investment mortgages, portfolio lender products, or paying off a hard-money bridge loan with a longer-term refinance. Each path treats seasoning and documentation differently, so the right choice depends on how fast you need capital out and how the property qualifies.

  1. DSCR loans qualify primarily on the property’s rental income rather than your personal income, and many DSCR lenders require only 3 to 6 months of seasoning, according to a refinance guide for investment property.
  2. Conventional cash-out refinances, including those following Fannie Mae’s cash-out guidelines, commonly require the existing mortgage to be at least 12 months old along with borrower-on-title requirements and maximum loan-to-value limits.
  3. Freddie Mac’s cash-out refinance guidance similarly sets LTV and debt-coverage underwriting constraints that determine how much of the appraised value a lender will actually lend against.

Seasoning windows vary by lender and product, typically running from 3 to 6 months for many DSCR programs up to 12 months for conventional cash-out refinancing, a gap that can determine whether your capital comes back in time to fund the next deal, per the refinance guide for investment property.

Appraisal risk is the other major variable. Use a conservative ARV estimate going in, request a pre-appraisal consultation when the lender offers one, and keep your comparable selections tight to similar square footage, age, and finish level in the immediate area.

A worked example: say you buy a property for $150,000 and spend $50,000 on rehab, for $200,000 total invested. If the ARV comes in at $260,000 and your lender allows 75% LTV on the refinance, the new loan size is $195,000. After paying off the original purchase and rehab financing, you recover a meaningful share of your invested capital, though the exact amount depends on your original financing terms.

BRRRR refinance capital recovery example

Before applying, prepare the appraisal order, signed lease, paid repair invoices, and before-and-after photos. Lenders and appraisers move faster with a complete file.

Repeat and scale: turning one cycle into a portfolio

Each completed cycle frees up capital for the next purchase, so the math worth tracking is how much cash you recover per deal and how many cycles your available capital can fund in a year. That pace depends on refinance speed, rehab timelines, and how much reserve you keep on hand.

  • Keep cash reserves per property rather than deploying every dollar recovered into the next deal.
  • Set a maximum leverage rule, such as never exceeding a fixed LTV across your portfolio, to avoid overexposure if rents soften.
  • Diversify across neighborhoods and tenant types rather than concentrating risk in one submarket.
  • Decide early whether you will self-manage renovations and leasing or hand them to a project manager as your unit count grows.

Bookkeeping, a vendor panel, and a simple dashboard tracking rent, expenses, and loan balances per property become necessary once you pass a handful of units, since spreadsheets alone stop scaling.

Why some BRRRR deals fail and how to stress-test yours

The biggest misconception is that you always get your full capital back at refinance. Appraisals, lender LTV limits, and rehab overruns routinely reduce that number, sometimes leaving cash permanently in the deal.

  • Appraisal shortfalls happen when the appraiser’s comparables come in below your projected ARV.
  • Cost overruns during rehab shrink the equity cushion you were counting on.
  • Refinance denial can occur if DSCR or income qualification falls short of lender thresholds.
  • Tenant turnover or vacancy right before refinance can weaken the income documentation lenders want.

Run a quick stress test before you buy: use a conservative ARV instead of your best case, add 20% to your rehab budget, and assume 6 to 9 months of vacancy or holding costs. If the deal still works under those assumptions, it has real margin.

Tax and accounting essentials for BRRRR investors

Depreciation materially affects your return and your tax bill. The IRS requires residential rental property placed in service after 1986 to use MACRS, depreciated on a straight-line basis over 27.5 years with a mid-month convention, according to IRS Publication 527. Rehab costs that count as capital improvements add to your depreciable basis rather than deducting immediately.

Residential rental property is depreciated using the straight-line method over a multi-decade recovery period, applying the mid-month convention in the month the property is placed in service.

Rental income and expenses are reported on Form 1040 Schedule E, and most individual investors use the cash method, deducting expenses in the year paid. Keep repairs separate from improvements in your records: a patched roof section is typically deductible immediately, while a full roof replacement is capitalized and depreciated, a distinction that matters at tax time and if the IRS ever reviews your filings. Investors who plan to accelerate depreciation on qualifying rehab components sometimes look into cost segregation strategies with a tax professional.

How a full-service manager supports BRRRR investors

Auben Realty has significant experience working with property owners and investors across multiple regional markets. Renovation oversight, vendor selection, and tenant placement are the points where BRRRR cycles most often slip, and having a team handle scope control, contractor coordination, and lease-up directly addresses those failure points.

— MediaBeast

Running your BRRRR cycles with support from Auben Realty

Aubenrealty

Rehab overruns and slow lease-ups are the two things most likely to stall your refinance timeline, and that is exactly where a dedicated team pays for itself. Services offered may include project management for renovation oversight and vendor coordination, tenant placement and leasing, and asset management support for investors managing multiple properties.

If you would rather hand off renovation oversight and ongoing property management than run every cycle yourself, see Auben Realty’s property management services to get started.

This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.

Sources

FAQ

What is the 70% rule for BRRRR?

The 70% rule says investors should pay no more than 70% of the after-repair value minus estimated repair costs. It is a quick screening tool to keep enough margin for financing costs and profit, not a guarantee of returns.

What is the 3-3-3 rule in real estate?

Definitions of the 3-3-3 rule vary and there is no single, widely recognized standard behind it. Treat any version you encounter as a rough guideline rather than an industry rule, and underwrite each deal on its own numbers instead.

Does the BRRRR method really work?

BRRRR can work when rehab stays on budget, the property appraises at or near the projected ARV, and the refinance loan meets lender seasoning and LTV requirements. It fails most often when rehab overruns or the refinance appraisal comes in lower than expected, so conservative underwriting upfront matters more than optimism.

How much money do you need to BRRRR?

You need enough cash or financing to cover the purchase, the full rehab budget plus a contingency, and holding costs until the property is rented and refinanced. The exact amount depends on the deal, but the refinance is designed to return a share of that capital once the property is stabilized and appraised, per Fannie Mae’s cash-out guidelines.

60.3% Concessions Give Renters the Edge in Houston Rental Market 2026

Renters hold the leverage in Houston right now. Landlords are offering concessions at some of the highest rates in the country, median asking rent has fallen for more than three years straight, and inventory keeps climbing. The number to watch is the metro concession rate, which recently topped 60%, a clear sign owners are competing hard to keep units filled.


TL;DR:

  • Concession rates in Houston have surged past 60%, indicating landlords are heavily incentivizing tenants amid rising supply and declining asking rents.
  • Asking rents have declined for 37 consecutive months, with median rent near $1,373, while rental inventory and concessions continue to grow.
  • Variations between neighborhoods significantly impact rents, with inner areas commanding premiums and newer suburbs offering more concessions due to increased competition.
  • Effective rent and vacancy rates are more telling than posted asking prices, guiding owners on whether to offer concessions or adjust rents.

Aubenrealty
Make Houston Rentals Easier to Manage
Auben Realty helps property owners handle management, renovations, and tenant placement with local market expertise and less hands-on involvement.

Table of Contents

Latest metrics: rents, concessions, CPI, and inventory

Houston’s rental numbers tell a consistent story: more supply, more competition among landlords, and softer pricing power. Median asking rent in the metro sat around $1,373 in August 2026, down 2.7% year over year, marking the 37th straight month of annual rent declines. At the same time, the share of listings offering concessions climbed to 60.3%, a jump of 19.4 percentage points from a year earlier, according to the same Realtor.com report.

That concession spike is not unique to Houston. Realtor.com’s national analysis found concessions rising in 39 of the 50 largest metros, with Houston among the markets posting the sharpest year-over-year increases, a sign that new supply is outpacing lease-up speed across much of the country.

Meanwhile, the CPI rent index for the Houston metro, tracked by the Bureau of Labor Statistics through FRED, offers a useful contrast: it measures rent inflation across existing leases, which typically moves more slowly than asking rents on vacant units. When CPI rent inflation still shows gains while asking rents fall, it usually means the softening is concentrated in new and turnover leases rather than the broader base of renewals.

On the supply side, HAR’s mid-2026 update found single-family leased listings rising while average lease prices held roughly steady, reinforcing that renters have more options without an across-the-board price collapse.

Metric Reading Source
Median asking rent (Aug 2026) $1,373, down 2.7% YoY Realtor.com
Metro concession rate (Aug 2026) 60.3%, up 19.4 points YoY Realtor.com
National concession trend Up in 39 of 50 metros Realtor.com
Single-family listings (mid-2026) Rising, average lease price steady HAR
  • Rents have declined for 37 consecutive months on an annual basis.
  • Concessions are near record levels, giving renters room to negotiate.
  • Single-family rental supply is expanding even as average asking prices hold flat.

Why the metrics look this way: jobs, supply, and affordability

The concession surge and flat pricing trace back to a straightforward supply-demand mismatch. Houston keeps adding jobs, which supports demand, but new rental units have arrived faster than the market can absorb them.

  • The Greater Houston Partnership reports 50,300 jobs added in the 12 months ending July 2026, with construction, administrative support, and health care among the leading contributors.
  • Multifamily completions and new single-family rental listings have pushed inventory higher across most submarkets.
  • Houston’s relative affordability compared with coastal metros continues to draw new residents, which cushions demand even as supply grows.

Pro Tip: Track effective rent, not just posted rent. A unit advertised at full price with two free months and waived fees can cost less monthly than a slightly cheaper unit with no concessions.

What the next 6 to 12 months could look like

Two scenarios are plausible, and the difference will show up in the same indicators driving today’s numbers.

  1. Renter-friendly conditions persist if new supply keeps arriving faster than job growth can absorb it, keeping concessions elevated and asking rents flat or lower.
  2. The market stabilizes if job growth outpaces new completions, gradually pulling concession rates down and firming up asking rents.
  3. Watch four indicators: the metro concession rate, the CPI rent index, months of supply in HAR’s data, and local job growth reported by the Greater Houston Partnership.

A meaningful drop in the concession rate, paired with steady job additions, would be the clearest early signal that leverage is shifting back toward landlords.

What renters and owners should do next

The current data points to specific moves on both sides of the lease.

  • Renters should compare at least three listings in a target submarket and ask directly about concessions before negotiating on base rent.
  • Owners should weigh a limited-time concession against a permanent rent cut, since concessions preserve the lease’s stated rent for future comps.
  • A small capital improvement, like updated flooring or lighting, can shorten vacancy without requiring a deep price cut.

Pro Tip: A common rule of thumb is to cap concession value at around one month’s rent spread across a 12-month lease rather than offering a larger upfront discount that permanently resets tenant expectations.

If a unit sits more than 30 days without strong showing activity, that is typically the point to reassess pricing or add a concession rather than waiting longer. Auben Realty’s leasing season guidance covers timing tactics that apply directly to this kind of market.

How a local manager reads these signals

A property management firm with extensive experience across multiple markets, including Houston, can provide informed perspectives on how concessions and vacancy interact. In practice, that often means pairing a targeted concession with a modest renovation, such as fresh paint or updated fixtures, to shorten time on market while protecting net operating income rather than cutting the base rent outright. Readers weighing their own approach can review Auben’s property management and project management services for a closer look at how that balance gets managed.

Technician installing updated rental bathroom fixture

Average rental prices by neighborhood

Metro-wide averages hide real differences between Houston submarkets. Inner Loop neighborhoods like Montrose, the Heights, and Midtown tend to command a premium over the metro median due to walkability and proximity to downtown and job centers. Suburban and outer-loop areas, including parts of Katy, Cypress, and Pearland, typically post rents closer to or below the metro average, reflecting newer supply and longer commutes. Energy Corridor and areas near major employers can swing with sector-specific hiring, while emerging areas with recent multifamily construction, such as parts of the East End, often show the steepest concessions because new buildings compete hardest for tenants. Because HAR and Realtor.com report metro-level figures rather than a full neighborhood breakdown, renters comparing specific submarkets should check current listings directly. Auben Realty’s rental listings page shows live examples of asking rents across the firm’s managed portfolio, which can serve as a useful reference point when comparing neighborhoods.

Average rental prices by neighborhood — overview diagram

Types of rental properties available in Houston

Houston’s rental stock spans a wide mix of property types, which is part of why metro averages can be misleading. Traditional apartment complexes, from garden-style to high-rise, make up the largest share of listings and are where most of the concession activity documented by Realtor.com is concentrated. Single-family rental homes have grown as a category, especially in suburban submarkets, and HAR’s data shows leased single-family listings rising through mid-2026. Townhomes and condos round out the market, often appealing to renters who want more space than an apartment without the maintenance of a standalone house. Build-to-rent communities, purpose-built single-family developments designed for long-term renters rather than buyers, have also expanded in the metro and add another layer of competition to the suburban rental supply.

Vacancy rates and what they mean for renters and owners

Rising inventory and elevated concessions both point to higher vacancy pressure across much of Houston’s rental stock, particularly in newer apartment communities still working through initial lease-up. When vacancy runs higher, landlords compete more aggressively on price and incentives, which is exactly what shows up in the concession data. For renters, higher vacancy translates directly into negotiating room: more available units mean more leverage to ask for a lower rate, waived fees, or a free month. For owners, sustained vacancy erodes net operating income even when posted rent stays flat, since an empty unit generates no revenue at all. That is why tracking effective rent, the actual income after concessions, matters more in a higher-vacancy environment than simply watching the asking price. Owners managing multiple units often find that a faster lease-up at a modest concession beats holding out for full price against a slower-moving pool of prospects.

Houston’s population growth continues to be driven by job opportunities in sectors like health care, construction, and administrative support, all named among the metro’s top contributors to the 50,300 jobs added in the year ending July 2026. That job growth draws a mix of new residents, from early-career workers renting their first apartment to relocating families weighing the buy-versus-rent decision. Houston’s relative affordability compared with coastal job centers continues to make renting locally attractive even as national migration patterns shift. Households priced out of homeownership by mortgage rates or home prices also add to rental demand, a dynamic explored further in Auben Realty’s comparison of renting versus buying affordability. Together, these forces keep baseline demand steady even as supply-side pressure keeps pricing power tilted toward tenants for now.

How local regulations shape the rental market

Texas does not have rent control, and Houston, like the rest of the state, cannot impose rent caps under current state law, so pricing in the metro is set entirely by supply and demand rather than regulatory limits. That absence of rent control is part of what allows landlords to respond quickly to softening demand with concessions rather than being locked into fixed pricing structures. Local regulations that do apply tend to focus on habitability standards, lease disclosure requirements, and eviction procedures rather than price controls. For owners and investors, this means Houston’s rental economics are driven by market fundamentals, like job growth, supply additions, and concession trends, more directly than in metros with rent stabilization rules. Auben Realty’s broader look at why Houston remains a strong investment market covers how this regulatory environment factors into longer-term investment decisions.

What renters and owners should watch beyond the metro numbers

Metro averages mask real variation between submarkets, so check concessions and days on market in your specific neighborhood rather than relying on citywide figures alone. Lower-income renters should weigh whether newer, concession-heavy units offer better value than older stock with lower base rent but fewer incentives. Typical market renters have more room to negotiate right now than the headline median rent suggests, so ask directly about concessions before signing.

— MediaBeast

How Auben Realty helps owners respond to these conditions

Property management firms may offer management, leasing, renovation oversight, and asset management services to owners navigating Houston’s current conditions. Experienced property management firms help owners manage vacancy and pricing decisions directly. Start with property management to see how it fits your portfolio.

Aubenrealty

Sources

FAQ

Is rent dropping in Houston?

Yes, median asking rent in Houston fell modestly year over year to roughly $1,373 in August 2026, marking 37 straight months of annual declines according to Realtor.com. Concessions have also risen sharply, adding further downward pressure on effective rent.

What is driving Houston’s high concession rates?

Rising rental supply, including new apartment completions and single-family listings, has outpaced lease-up speed, pushing landlords to offer concessions to fill units faster. Houston’s concession rate reached 60.3% in August 2026, one of the sharper increases among major U.S. metros tracked by Realtor.com’s national analysis.

Which cities have the highest rental demand?

Rental demand tends to run highest in metros with strong job growth and relative affordability, which is part of why Houston continues to attract renters despite softer pricing. Demand varies by local job market conditions, so checking metro-specific job growth and vacancy data gives a clearer picture than national rankings alone.

What is the best rental market in Texas for investors right now?

There is no single definitive answer, since the right market depends on an investor’s goals, but Houston’s combination of job growth and relative affordability makes it a market worth close consideration. Auben Realty’s analysis of Houston as an investment market covers the factors supporting that case in more detail.

How can owners tell if they should offer concessions or lower rent?

A short-term concession, like a free month or waived fees, preserves the lease’s stated rent for future comparisons, while a base rent cut resets tenant expectations permanently. Owners typically favor concessions when vacancy is temporary and tied to seasonal leasing patterns, reserving rent cuts for units that have sat unleased well beyond typical days-on-market in their submarket.